Editorially maintained information about Fred Loya Insurance names, official contacts, and policy verification.
Created: March 5, 2016
Updated: September 12, 2026
Fred Loyal Insurance
Fred Loya Insurance
Company Name Check
The LoyalInsurance.org Editorial Team maintains consumer-focused information about insurance companies,
policy documents, contact paths, coverage, and claims.
LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance
or any insurer. Always use the company name, policy number, and contact information shown on your own policy documents.
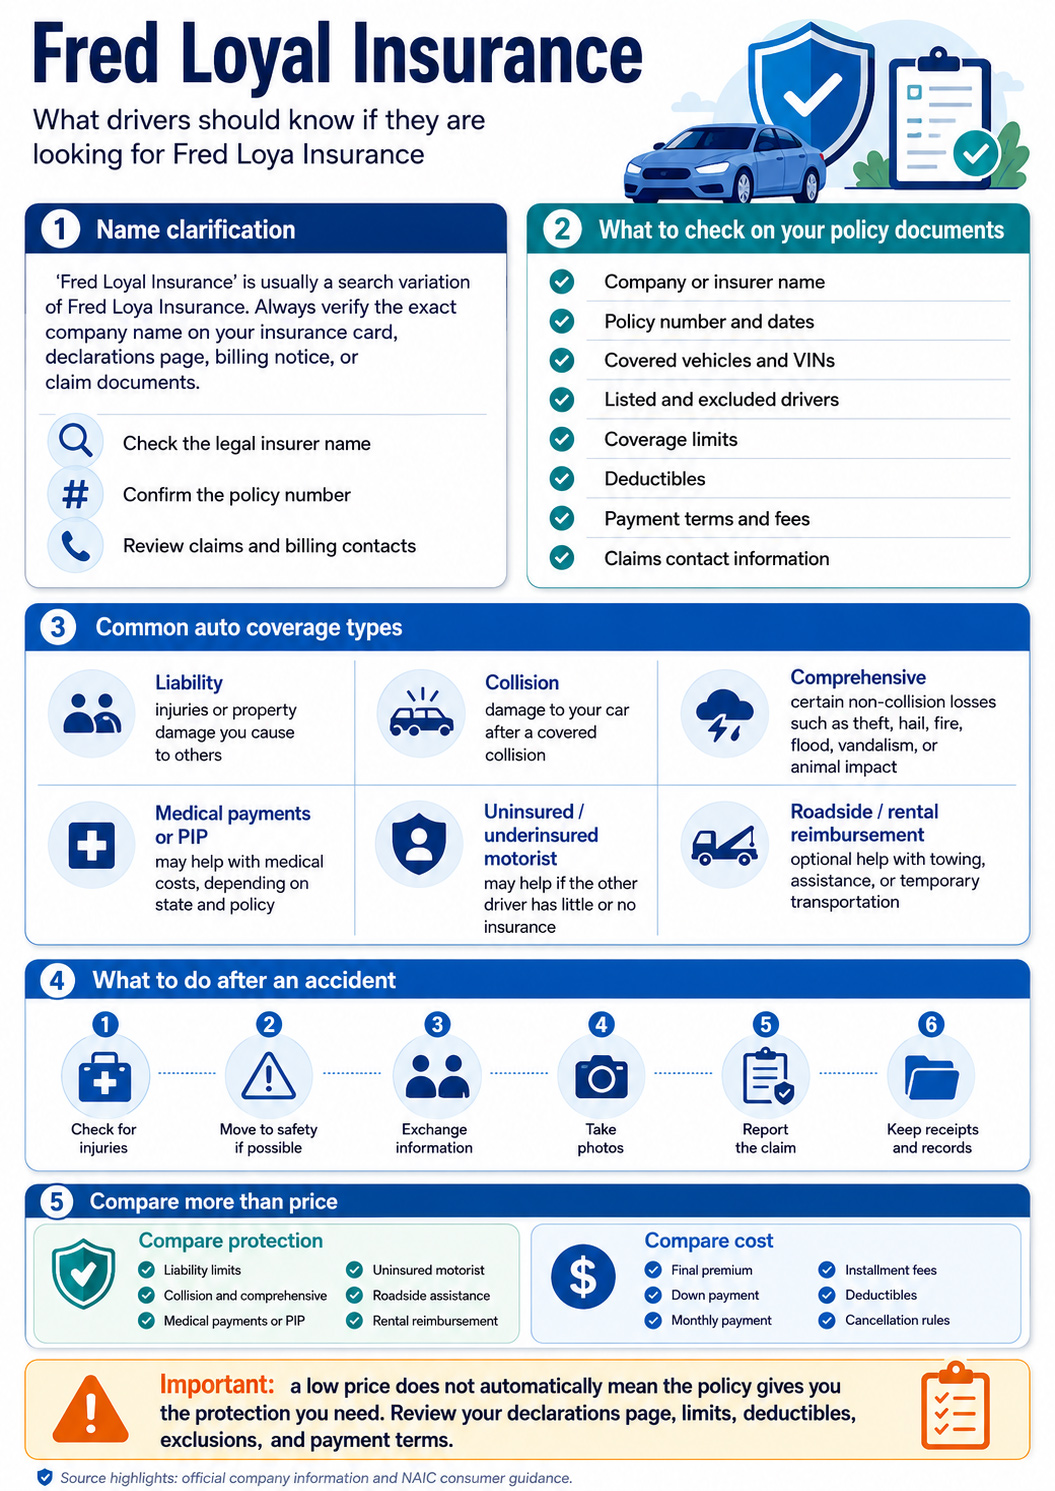
Name Clarification
If you searched for Fred Loyal Insurance while trying to reach the auto insurer,
the official company website uses the name Fred Loya Insurance.
Use the exact company name shown on your insurance card, declarations page, bill, or claim correspondence
when checking a policy, payment, office, or claim.
Fred Loya’s official contact page currently lists 1-800-444-4040 for quotes and customer service
and 1-800-880-0472 for claims. Its website also provides an official office finder and online account tools.
Official brandFred Loya Insurance
Customer service1-800-444-4040
Claims1-800-880-0472
Best verificationYour policy documents
Fred Loyal Insurance vs. Fred Loya Insurance
“Fred Loyal Insurance” is not the name used on Fred Loya’s official website.
The public-facing brand is Fred Loya Insurance, while official company materials also use
the broader Loya Insurance Group name.
The distinction matters because similar Loya-related names can appear on insurance documents.
Fred Loya’s claims page says Loya Insurance Group handles claims for subsidiaries including
Loya Insurance Company, Fred Loya Insurance, and
Young America Insurance. The relationship between
Loya Insurance Company and Fred Loya Insurance
is relevant when the legal insurer on a policy differs from the consumer-facing brand.
Do not rely on spelling alone: The legal insurer shown on the declarations page or policy forms
is more important than the brand name used in an advertisement, search result, or office sign.
Official Fred Loya Pages for Common Tasks
If you were looking for Fred Loya Insurance, use the official page that matches
what you need. Payments, claims, office information, account access, and contact
details can change, so the current Fred Loya website is the best place to verify
time-sensitive information.
Payments, ID cards, declarations, policy details, and payment summary tools.
How to Verify the Name on an Insurance Document
If the document in front of you says Fred Loya, Loya Insurance Company, Young America Insurance,
or another insurer name, do not rewrite that name based on what you remember seeing online.
Use the exact company name printed on the document when discussing a policy, payment, or claim.
Declarations page Check the insurer name, policy number, effective dates, vehicles, drivers, limits, and deductibles.
Insurance card Confirm the insurer name and policy number before using it as proof of insurance.
Billing notice Match the policy number and insured name before submitting a payment.
Claim correspondence Keep the claim number, assigned adjuster information, and insurer name together.
Website domain For Fred Loya online services, verify that you are on the official fredloya.com domain.
Frequently Asked Questions About “Fred Loyal Insurance”
Is the auto insurer called Fred Loyal Insurance?
The official website uses the name Fred Loya Insurance. If you entered “Fred Loyal Insurance” while looking for that company,
use the official Fred Loya spelling when searching for its website, offices, customer service, or claims information.
What is the official Fred Loya website?
The current official website is FredLoya.com.
What is the Fred Loya customer service number?
Fred Loya currently lists 1-800-444-4040 for quotes and customer service.
What is the Fred Loya claims number?
Fred Loya currently lists 1-800-880-0472 for filing or checking an auto insurance claim.
Why might a different Loya-related company name appear on my documents?
Fred Loya’s claims page says Loya Insurance Group handles claims for subsidiaries including Loya Insurance Company,
Fred Loya Insurance, and Young America Insurance. Use the exact insurer name shown on your own policy documents.
Optional: Compare Other Coverage
Compare Auto Insurance Quotes by ZIP Code
If you are shopping for alternatives rather than trying to service an existing Fred Loya policy,
enter your ZIP code to compare auto insurance quote options. This comparison is separate from
Fred Loya’s official website and policy-service tools.
Compare equivalent limits, deductibles, total premium, and policy terms before choosing an insurer.
Sources
This page uses current Fred Loya public information to clarify the company name and identify the appropriate
official service channels. Contact details and online tools can change, so verify time-sensitive information
on the current Fred Loya website.
Editorially maintained information about Fred Loya Insurance, coverage, claims, service access, and consumer feedback.
Created: March 5, 2016
Updated: September 12, 2026
Fred Loya Review
Auto Insurance
Consumer Comparison
The LoyalInsurance.org Editorial Team maintains consumer-focused information about auto insurers,
coverage, claims, service access, policy terms, and shopping decisions.
LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance
or any insurer. Pricing, coverage, discounts, claims outcomes, fees, and service experiences vary by state,
policy, location, driver, and claim facts.
Fred Loya Insurance Review
Fred Loya Insurance is an auto-focused insurance group that says it began with one storefront
in El Paso, Texas, in 1974 and has expanded to more than 800 offices across 12 states.
Its public website emphasizes basic auto insurance, local offices, same-day policy issuance,
no-credit-check options, and several common discounts.
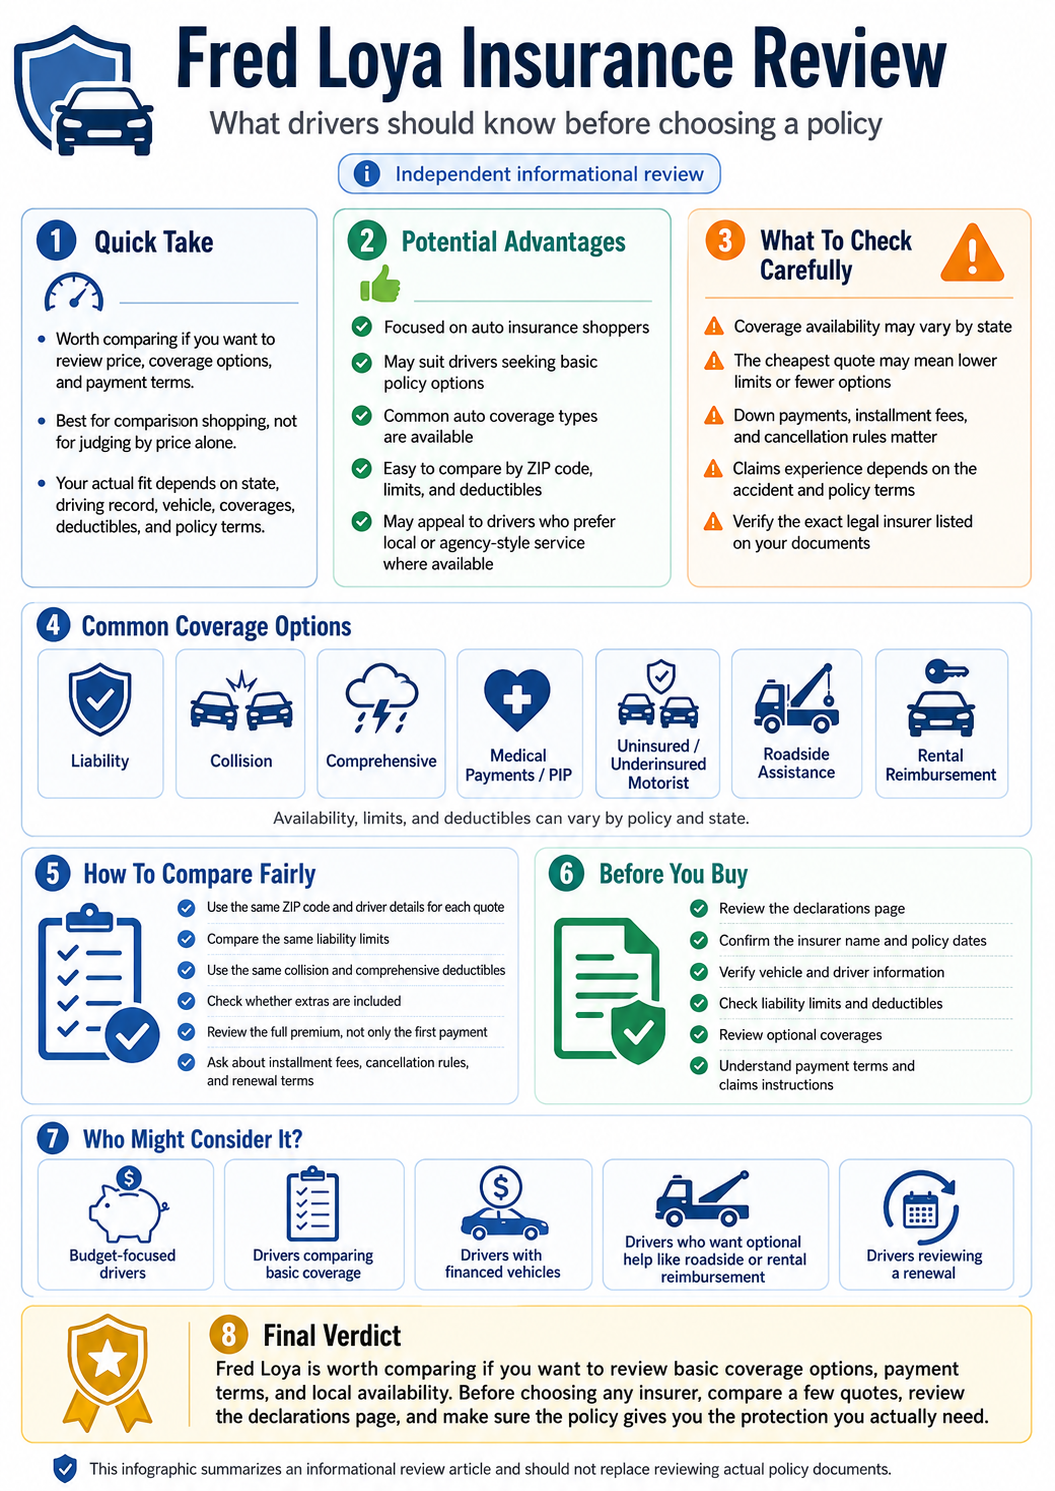
The company can be worth comparing for drivers who value local office access or are shopping for straightforward
auto coverage, but price should not be the only deciding factor. Coverage limits, deductibles, payment terms,
claims access, legal insurer name, and consumer-service signals should all be checked before buying.
Founded1974
Office network800+ offices / 12 states
Primary focusPersonal auto insurance
BBB snapshotB rating / not accredited
Fred Loya Insurance at a Glance
Fred Loya’s current website says the group has sold more than 4.5 million policies and operates in
Alabama, Arizona, California, Colorado, Georgia, Illinois, Indiana, New Mexico, Nevada, Ohio, Oklahoma, and Texas.
Its office model includes stand-alone locations and agencies inside or near large retail stores and supermarkets.
The company markets immediate coverage, saying an auto policy can be issued the same day,
and says policies can be issued with no credit check. It also advertises prior-insurance,
homeowner, multi-car, and good-driver discounts, while noting that discounts vary by state and restrictions apply.
What those marketing points do not tell you: They do not establish your final rate,
eligibility, coverage limits, deductible, fees, or claim outcome. Those details come from the quote,
declarations page, policy forms, and insurer underwriting.
Potential Strengths
Large local-office network
Fred Loya currently lists more than 800 offices in 12 states. That can be useful for drivers who prefer
in-person service rather than handling every policy question online.
Auto-focused product
The company’s public materials are centered on personal auto insurance rather than a broad mix of unrelated products.
That makes the website and office network relatively focused on auto-policy questions.
Same-day policy availability
Fred Loya states that policies can be issued the same day. That can matter when a driver needs replacement coverage
quickly, although the policy should still be confirmed before relying on it.
No-credit-check option
The current website says policies can be issued with no credit check. This does not mean every rating factor
is ignored or that every applicant receives the same rate.
Important Drawbacks and Consumer-Service Signals
A useful insurer review should include current independent feedback, not only company marketing.
As of this September 2026 review, the Better Business Bureau profile for Fred Loya Insurance, LP.
shows a B rating and says the business is not BBB accredited.
BBB’s complaint page currently reports 343 complaints in the last three years,
including 59 closed in the last 12 months.
BBB’s customer-review page currently shows an average rating of 1.01 out of 5
from 134 customer reviews. Those numbers can change and should not be treated as a regulatory
complaint ratio or as proof that every customer has the same experience. BBB reviews are self-selected,
and the headquarters profile says its complaint data can include corporate-owned locations.
How to use complaint data: Treat it as one comparison signal. Check your state insurance department,
policy documents, claims contacts, and current quote alongside BBB information rather than relying on a single rating.
Coverage Available Through Fred Loya
Fred Loya’s current public website lists liability, comprehensive, collision, medical coverage,
personal injury protection, rental reimbursement, and roadside assistance among its auto insurance categories.
Exact availability, limits, deductibles, exclusions, and pricing can vary by state and policy.
Coverage
What It Generally Addresses
What to Verify
Liability
Covered bodily injury or property damage for which the insured is legally responsible.
Dollar limits, exclusions, state requirements, and whether higher limits are available.
Collision
Covered collision damage to the insured vehicle.
Deductible, vehicle value, lender requirements, and exclusions.
Comprehensive
Certain covered non-collision losses such as theft, weather, vandalism, fire, or animal impact.
Deductible, covered causes of loss, and exclusions.
Medical / PIP
Specified medical or injury-related benefits depending on state law and policy terms.
Availability, limits, eligibility, and whether coverage is required or optional.
Rental reimbursement
Specified rental-car costs when the policy benefit applies after a covered loss.
Daily or total limits, qualifying circumstances, and exclusions.
Roadside assistance
Specified roadside services such as towing, fuel delivery, flat-tire help, or lock-out service.
Whether it is included or optional and which service limits apply.
“Full Coverage” Needs a Closer Look
Fred Loya’s own FAQ says there is no single policy that literally provides “full coverage.”
Every policy has limits, deductibles, and exclusions. That is a useful standard for evaluating any quote:
focus on the actual coverage shown rather than a broad label.
A quote that includes liability, collision, and comprehensive can still differ substantially from another policy
because the liability limits, deductibles, optional benefits, excluded drivers, policy term, and payment structure may differ.
Claims Process and Access
Fred Loya currently lists 1-800-880-0472 for reporting claims.
Its claims page publishes hours of Monday through Friday, 8:00 a.m. to 7:00 p.m. MST
and Saturday, 8:00 a.m. to 4:00 p.m. MST.
Claims reporting therefore does not appear to be presented as a 24/7 live-agent service on the current claims page.
Fred Loya says a liability claims adjuster is assigned to the loss report and will contact the claimant within 24 hours.
Its published process includes policy review, accident statements, vehicle-damage estimates, evidence gathering,
and a final claim disposition based on the liability investigation.
Fred Loya currently lists 1-800-444-4040 for quotes and customer service.
Its contact page says the group has more than 800 offices in 12 states, while the location finder provides
branch addresses, local phone numbers, hours, language information, directions, and quote access.
Local access can be useful, but it should not substitute for checking the policy itself.
Office convenience does not determine the liability limits, deductible, exclusions, legal insurer,
or how a future claim will be resolved.
How to Compare Fred Loya With Another Insurer
Compare equivalent coverage rather than comparing only monthly payments.
Use the same drivers, vehicles, liability limits, physical-damage coverage, deductibles,
and major optional benefits whenever possible.
Compare protection
Bodily injury and property-damage limits
Collision and comprehensive
Deductibles
Medical or PIP coverage
UM/UIM where available
Rental and roadside benefits
Compare service and cost
Total policy premium
Down payment and installment schedule
Applicable fees
Claims reporting access
Local office availability
Complaint and customer-feedback signals
Who May Want to Compare Fred Loya?
Fred Loya may be worth including in a comparison if you live in one of its 12 operating states,
prefer access to a physical office, want an auto-focused insurer, or are interested in its advertised
no-credit-check and same-day-policy options.
It deserves closer comparison if claims access outside the published live-agent hours is important to you,
if you place substantial weight on BBB customer feedback, or if another insurer offers materially stronger
limits, benefits, or pricing for equivalent coverage.
What to Check Before Buying
Policy details that matter
Legal insurer name shown on the policy
Effective and expiration dates
Covered vehicles and VINs
Listed and excluded drivers
Liability limits
Collision and comprehensive coverage and deductibles, if included
Medical, UM/UIM, rental, roadside, or other optional benefits, if included
Total premium and payment schedule
Applicable fees and cancellation terms
Claim-reporting instructions
Verdict
Fred Loya has a long operating history, a large physical-office network, and an auto-focused product lineup.
Its same-day-policy and no-credit-check marketing may appeal to some drivers, particularly those who prefer
local access or straightforward auto-insurance shopping.
The tradeoff is that current BBB feedback is weak, and the published claims line has defined live-agent hours
rather than being presented as 24/7. For that reason, Fred Loya is better treated as an insurer to
compare carefully rather than one to choose or reject based on brand recognition alone.
The deciding factors should be your actual quote, coverage limits, deductible, total premium, policy documents,
and the service features that matter to you.
Frequently Asked Questions About Fred Loya Insurance
Is Fred Loya Insurance a good company?
There is no single answer for every driver. Fred Loya has a large office network and auto-focused products,
but current BBB feedback is poor. Compare the actual policy, price, service access, and consumer-feedback signals
against other insurers available to you.
Is Fred Loya BBB accredited?
No. The current BBB headquarters profile says Fred Loya Insurance, LP. is not BBB accredited
and shows a B rating. BBB ratings and complaint counts can change over time.
Does Fred Loya have many complaints?
BBB’s headquarters complaint page currently shows hundreds of complaints over the last three years.
BBB says the profile includes headquarters and corporate-owned locations, so the number should be treated
as one consumer-feedback signal rather than a regulatory complaint ratio.
Does Fred Loya offer “full coverage”?
Fred Loya says there is no single policy that provides literal “full coverage.”
Every policy has limits, deductibles, and exclusions, so check the actual declarations page and policy forms.
What is the Fred Loya claims phone number?
Fred Loya currently lists 1-800-880-0472 for claims. Its published claims hours are Monday through Friday,
8:00 a.m. to 7:00 p.m. MST, and Saturday, 8:00 a.m. to 4:00 p.m. MST.
Compare Quote Options
Compare Auto Insurance Quotes by ZIP Code
Enter your ZIP code to compare auto insurance options.
Match equivalent limits, deductibles, and policy features before choosing an insurer.
Compare the total premium, coverage, deductible, service access, and policy terms—not just the first payment.
Sources
This article uses current Fred Loya public information, current BBB consumer-feedback data,
and consumer insurance resources. Ratings, reviews, complaints, office availability, discounts,
and company information can change, so time-sensitive details should be checked directly.
Editorially maintained information about basic auto coverage, liability limits, deductibles, and policy choices.
Created: July 10, 2015
Updated: September 12, 2026
Basic Car Insurance
Liability Coverage
Policy Comparison
The LoyalInsurance.org Editorial Team maintains consumer-focused information about auto insurance coverage,
liability limits, deductibles, vehicle protection, lender requirements, and policy shopping.
LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance
or any insurer. Coverage availability, pricing, limits, deductibles, exclusions, and policy terms vary by
state, insurer, policy, vehicle, and driver.
Basic Car Insurance
Fred Loya currently markets “Basic Car Insurance And More”, but “basic car insurance”
should not be treated as one fixed policy package. The actual policy depends on the state,
liability limits, vehicle, deductibles, optional coverage, and the insurer shown on the policy documents.
For many drivers, a basic policy starts with liability coverage. Fred Loya’s current quote flow can also
present options such as collision, comprehensive, uninsured or underinsured motorist coverage,
medical payments, personal injury protection, rental, and towing, depending on the quote and state.
The declarations page is what confirms which coverages were actually purchased.
Starting pointLiability coverage
CompareLimits and deductibles
Do not assume“Full coverage”
Final authorityPolicy documents
Basic Coverage Is Not the Same as Minimum Coverage
“Minimum coverage” usually means the lowest insurance or financial-responsibility requirement established
by a state. “Basic coverage” is a broader shopping term and can describe anything from minimum liability
to liability plus selected optional protections.
The NAIC notes that each state sets its own auto insurance rules and that most states require at least
a basic level of coverage. It also explains that consumers often buy more than the minimum because a legal
minimum does not necessarily match the financial risk of a serious accident.[1]
Minimum does not mean sufficient: A policy can satisfy the legal requirement and still leave
substantial costs above the liability limit. Compare the actual dollar limits rather than relying on labels
such as “basic,” “minimum,” or “full coverage.”
What Fred Loya Currently Shows as Coverage Options
Fred Loya’s public website currently lists liability, comprehensive, collision, medical coverage,
personal injury protection, rental reimbursement, and roadside assistance among its auto insurance categories.
Its quote flow also presents uninsured/underinsured motorist and other coverage choices.[2][3]
Coverage
What It Generally Addresses
What to Confirm
Bodily injury liability
Covered injuries you cause to other people.
Per-person and per-accident limits, exclusions, and state requirements.
Property damage liability
Covered damage you cause to another person’s vehicle or property.
The property-damage limit and whether higher limits are available.
Collision
Covered collision damage to your insured vehicle.
Whether it is included and which deductible applies.
Comprehensive
Certain covered non-collision losses such as theft, hail, fire, vandalism, flood, or animal impact.
Deductible, covered causes of loss, exclusions, and vehicle value.
Medical or PIP
Covered medical or injury-related expenses, depending on state law and policy terms.
Whether the coverage is required, optional, rejectable, or available in the state.
UM/UIM
Certain losses involving an uninsured or underinsured driver.
Availability, limits, state requirements, and any rejection options.
Rental or roadside
Specified temporary transportation or roadside-service expenses when the coverage applies.
Limits, qualifying events, exclusions, and whether the option was actually purchased.
Liability Is Usually the Foundation
Liability coverage generally focuses on covered bodily injury or property damage for which the insured
is legally responsible. It should not be confused with coverage for damage to the insured vehicle.
Fred Loya’s FAQ states that liability covers third-party bodily injury and that Personal Injury Protection
or Medical Payments may be purchased to address the insured’s own medical costs where available.
It also says there is no single policy that provides “full coverage”; policies have limits, deductibles,
and exclusions.[4]
Liability may address
Covered bodily injury to another person
Covered damage to another person’s vehicle
Covered damage to other property
Policy obligations associated with a covered liability claim
Liability alone should not be assumed to cover
Repairs to your own vehicle
Your own medical expenses
Rental reimbursement
Roadside assistance
Losses above the policy limits
When Basic Liability May Leave a Large Gap
A lower-cost liability policy can be a reasonable choice for some paid-off vehicles, but the tradeoff is important:
damage to your own car may remain your responsibility if you do not carry applicable physical-damage coverage.
Low liability limits can also leave you personally exposed when a covered loss exceeds the policy limit.
The amount of
auto insurance coverage that fits your situation
depends on more than the legal minimum. Vehicle value, assets, lender requirements, deductible tolerance,
driving exposure, and the amount of risk you can absorb all matter.
Financed or Leased Vehicles
Fred Loya’s current FAQ says a lienholder may require physical-damage coverage on a financed vehicle.
Its description includes collision and damage from events such as hail, flood, and vandalism, subject to
policy terms and a deductible.[4]
Before reducing coverage on a financed vehicle
Check the loan or lease agreement.
Confirm whether collision and comprehensive are required.
Check any maximum deductible allowed by the lender.
Confirm that the lienholder information is correct.
Do not remove required coverage solely to lower the premium.
How to Compare Basic Auto Insurance Quotes
A fair comparison uses the same drivers, vehicles, liability limits, physical-damage coverage,
deductibles, and major optional benefits whenever possible. A lower monthly payment can simply mean
the quote contains less coverage.
Liability limits Compare the actual dollar limits, not just the coverage name.
Deductibles Match collision and comprehensive deductibles when comparing physical-damage coverage.
Optional coverage Check medical, UM/UIM, rental, roadside, and other options separately.
Policy term Confirm the length of each quoted policy.
Total premium Compare the full policy cost, not just the down payment or monthly installment.
Fees Check applicable installment or policy charges shown in the quote or policy documents.
Excluded drivers Confirm who is and is not covered to drive the insured vehicle.
Effective date Make sure coverage starts when you expect it to start.
Ways to Lower Cost Without Relying Only on Minimum Coverage
Triple-I recommends shopping around, checking insurance costs before buying a vehicle,
considering higher deductibles that you could afford, evaluating collision or comprehensive on older vehicles,
and asking about discounts. It also recommends getting at least three price quotes when shopping.[5]
Cost Decision
Possible Benefit
Tradeoff to Check
Compare insurers
Different insurers can price the same risk differently.
Make sure the coverage being compared is equivalent.
Higher deductible
Can reduce some collision or comprehensive premiums.
You pay more out of pocket after a covered loss.
Older vehicle coverage
Dropping physical damage can reduce premium on some paid-off vehicles.
You may have no policy payment for your own vehicle after certain losses.
Discounts
Qualifying discounts can reduce the premium.
Eligibility and availability vary by company and state.
If You Prefer In-Person Help
Some drivers prefer to discuss limits, deductibles, and required documents face to face.
A
nearby Loya insurance office
may be useful for quote or policy questions, but confirm the specific branch, hours, and service you need before visiting.
What to Check on the Policy Before Buying
Policy details that matter
Legal insurer name
Policy effective and expiration dates
Covered vehicles and VINs
Listed and excluded drivers
Bodily injury and property-damage liability limits
Collision and comprehensive coverage and deductibles, if included
Medical, UM/UIM, rental, roadside, or other optional coverage, if included
Total premium and payment schedule
Claim-reporting information
Bottom line: “Basic” should describe a simpler coverage structure, not a reason to ignore limits,
exclusions, deductibles, lender requirements, or the cost of a serious loss.
Frequently Asked Questions About Loya Basic Car Insurance
Is Loya basic car insurance one specific policy?
Fred Loya markets “Basic Car Insurance And More,” but the public website does not describe one fixed policy package
that every customer receives. The issued policy and declarations page determine the actual coverage.
Is basic insurance the same as state-minimum coverage?
Not necessarily. Minimum coverage is tied to state requirements. A basic policy can include the minimum,
higher liability limits, or selected optional coverage depending on the quote and policy.
Does liability insurance repair my own car?
Liability generally addresses covered injuries or property damage caused to others.
Damage to your own vehicle ordinarily requires applicable physical-damage coverage such as collision
or comprehensive, depending on the loss and policy.
What does Fred Loya mean by “full coverage”?
Fred Loya’s FAQ says there is no policy that literally provides “full coverage.”
Every policy has limits, deductibles, and exclusions.
Do financed vehicles need more than liability?
They often do. Fred Loya’s FAQ says lienholders may require physical-damage coverage.
Check the finance or lease agreement before reducing coverage.
Compare Quote Options
Compare Basic Auto Insurance Quotes by ZIP Code
Enter your ZIP code to compare auto insurance quote options.
Check equivalent liability limits, deductibles, optional coverage, and total premium before choosing a policy.
Compare the actual coverage and policy terms, not only the first payment.
Sources
This article uses current Fred Loya public coverage information and consumer auto-insurance resources.
Actual coverage depends on the issued policy, state rules, limits, deductibles, exclusions, and endorsements.
Editorially maintained information about auto insurance pricing factors, coverage choices, and quote comparison.
Created: May 17, 2015
Updated: September 12, 2026
Car Insurance Calculator
Pricing Factors
Quote Comparison
The LoyalInsurance.org Editorial Team maintains consumer-focused information about auto insurance pricing,
coverage limits, deductibles, vehicle factors, prior insurance, and policy shopping.
LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance
or any insurer. This page does not calculate an insurer-approved premium. Actual rates depend on the insurer,
state rules, driver and vehicle information, selected coverage, discounts, and underwriting.
Car Insurance Cost Factors
A car insurance calculator can be useful for organizing the factors that may affect a quote,
but an independent website cannot reliably calculate a Fred Loya premium without the insurer’s
current rating rules and underwriting data.
This page therefore separates two things: the factors that commonly influence auto insurance pricing
and the actual quote you receive from an insurer. The interactive tool below creates a personalized
cost-factor summary without inventing a dollar premium.
Useful forPlanning scenarios
CompareEquivalent coverage
Not providedFake dollar premiums
Final stepGet insurer quotes
What Can Affect a Car Insurance Quote?
The NAIC identifies location, age, driving experience, driving record, claims history,
previous insurance coverage, vehicle type, vehicle use, miles driven, selected coverage,
and deductibles among common auto insurance rating factors. Which factors may be used,
and how much weight they receive, can differ by insurer and state.[1]
Triple-I likewise notes that driving record, vehicle use, location, age, vehicle type,
coverage amount, deductibles, and other permitted rating information can affect the price
of an auto policy.[2]
Location Territory, repair costs, theft, crashes, weather, and other local loss patterns can affect pricing.
Driving record Tickets, accidents, and serious violations can affect the insurer’s assessment of risk.
Vehicle Value, repair cost, theft experience, safety characteristics, and vehicle use can matter.
Coverage Higher limits and added physical-damage or optional coverage generally change the premium.
Deductible A higher deductible can reduce some physical-damage premiums but increases out-of-pocket risk after a covered loss.
Prior insurance Previous coverage is one of the rating factors identified by the NAIC.
Calculator Estimate vs. Actual Quote
Tool
What It Can Do
What It Cannot Confirm
Cost-factor calculator
Organize the driver, vehicle, coverage, and deductible factors that may influence pricing.
It cannot calculate the insurer’s filed rate, underwriting result, discounts, or final premium.
Online quote
Use more detailed information to produce a preliminary or current insurer price.
The price may still change if information, eligibility, discounts, or policy choices change.
Issued policy
Show the legal insurer, policy period, premium, limits, deductibles, vehicles, and other contract details.
It should not be replaced by an estimate or marketing summary.
Coverage Choices That Can Change the Price
Fred Loya currently describes liability, comprehensive, collision, medical coverage,
personal injury protection, rental reimbursement, and roadside assistance among its auto insurance categories.
Availability and policy terms can vary by state and policy.[3]
Coverage Choice
Pricing Consideration
What to Compare
Liability limits
Changing the amount of liability protection can change the premium.
Compare equivalent bodily injury and property-damage limits across quotes.
Collision
Adding physical-damage protection for covered collisions adds coverage that liability-only policies do not provide.
Check the deductible, vehicle value, and lender requirements.
Comprehensive
Coverage for certain non-collision losses changes both protection and cost.
Compare the deductible and covered causes of loss.
Medical or PIP
Availability and requirements depend on the state and policy.
Check the limit, eligibility, and whether the coverage is required, optional, or rejectable.
Rental or roadside
Optional benefits can add cost but may reduce certain out-of-pocket expenses when they apply.
Compare limits, covered events, and exclusions.
Financed or Leased Vehicles
Fred Loya’s current FAQ says a lienholder may require physical-damage coverage on a financed vehicle.
Its description includes vehicle damage from hail, flood, vandalism, and collision, subject to the policy
and deductible.[4]
That means a calculator scenario using liability-only coverage may not be appropriate for a financed or leased vehicle.
Check the loan or lease agreement before removing collision or comprehensive coverage simply to lower the premium.
Before Buying a Vehicle, Check Insurance Costs Too
Triple-I recommends checking insurance costs before buying a new or used vehicle because vehicle price,
repair cost, theft likelihood, and safety characteristics can affect insurance pricing. It also recommends
comparing prices from multiple insurers rather than shopping on price alone.[5]
Include these costs in the vehicle budget
Vehicle payment
Auto insurance premium
Fuel or charging
Registration and taxes
Maintenance and repairs
Deductible you would need after a covered claim
Car Insurance Cost Factor Calculator
Select a few details below. The tool will identify pricing factors and policy questions that deserve attention.
It deliberately does not produce a dollar estimate because this site does not have an insurer’s
current rating model.
Planning Tool
Build Your Cost-Factor Summary
This tool identifies general pricing considerations only. It does not calculate an insurer rate,
premium, discount, eligibility decision, or binding quote.
Ways to Lower Auto Insurance Costs
Triple-I recommends shopping around, checking insurance costs before buying a vehicle,
considering higher deductibles you could afford, evaluating collision or comprehensive on older vehicles,
and asking about discounts. It also recommends getting at least three price quotes.[5]
Compare savings without losing sight of coverage
Use equivalent liability limits when comparing insurers.
Check the total policy premium, not only the first payment.
Choose a deductible you could actually pay after a claim.
Ask which discounts are already included and which require verification.
Check lender requirements before removing physical-damage coverage.
Using Estimates When You Are Changing Insurers
An estimate can help organize the comparison, but the replacement policy must be active before the old one is canceled.
If the calculator is part of a planned insurer change, the timing steps for
switching car insurance without a coverage gap
matter more than the preliminary estimate itself.
What to Check Before Choosing a Policy
Policy details that matter more than an estimate
The legal insurer name
Policy effective and expiration dates
Covered vehicles and listed or excluded drivers
Bodily injury and property-damage liability limits
Collision and comprehensive coverage and deductibles
Optional medical, UM/UIM, rental, or roadside benefits when applicable
Total premium, down payment, installment charges, and payment schedule
Claim-reporting information
Frequently Asked Questions About Car Insurance Calculators
Is this an official Fred Loya calculator?
No. LoyalInsurance.org is independent. The interactive tool on this page summarizes general cost factors
and does not use Fred Loya’s proprietary rating or underwriting system.
Why does the calculator no longer show a dollar estimate?
A dollar premium would require current insurer rates, rating factors, state rules, underwriting data,
discounts, and detailed applicant information. Inventing a dollar range from simplified multipliers
would create false precision.
What information commonly affects a quote?
Common factors include location, driving record, claims history, vehicle type and use, prior insurance,
selected coverage, deductibles, and other permitted driver information. State rules can limit which factors may be used.
Should I check insurance before buying a vehicle?
Yes. Triple-I recommends comparing insurance costs before buying a new or used vehicle because insurance can materially
change the total cost of ownership.
How should I compare live quotes?
Use the same drivers, vehicle, liability limits, physical-damage coverage, deductibles, and major optional benefits
whenever possible, then compare the total premium and policy terms.
Sources
This page uses current consumer insurance resources and Fred Loya public coverage information.
Actual rates and eligibility must be obtained from an insurer or authorized quote process.
Editorially maintained information about changing auto insurers, avoiding coverage gaps, and comparing policies.
Created: December 2, 2014
Updated: September 12, 2026
Switch Car Insurance
Coverage Gaps
Policy Comparison
The LoyalInsurance.org Editorial Team maintains consumer-focused information about auto insurance costs,
policy changes, coverage limits, deductibles, cancellation questions, and practical shopping decisions.
LoyalInsurance.org is an independent informational website and is not affiliated with any insurer.
Cancellation rules, refunds, notice requirements, fees, lender requirements, and policy terms can vary
by state, insurer, policy, and customer situation.
Switching Car Insurance
Switching car insurance does not have to wait until renewal, but the timing matters.
The safest sequence is to compare policies, buy the replacement coverage, confirm its effective date
and proof of insurance, and only then cancel the old policy for the correct date.
The NAIC notes that consumers can cancel an auto policy before its normal expiration date and that a partial
premium refund may apply after cancellation, depending on the policy and state rules. The bigger risk is
allowing the old policy to end before the new one is actually in force.
PriorityAvoid a coverage gap
CompareEquivalent coverage
ConfirmNew effective date
KeepProof and cancellation records
When Does Switching Car Insurance Make Sense?
Common reasons include a large renewal increase, a vehicle change, adding or removing a driver,
moving, paying off a loan, changes in annual mileage, a change in coverage needs, or dissatisfaction
with service. None of those automatically means another insurer will be cheaper, so compare the full
policy rather than assuming a lower advertised payment is a better deal.
Shopping before the final days of the current policy gives you more time to compare limits,
deductibles, optional coverage, payment schedules, insurer requirements, and the exact effective date
of the replacement policy.
Timing matters: Do not cancel the current policy because you received a quote.
A quote is not the same thing as active coverage. Wait until the replacement policy has been issued,
its effective date is confirmed, and you have proof of insurance.
How to Switch Car Insurance Without a Coverage Gap
Step
What to Do
Why It Matters
1. Check the current policy
Note the expiration date, limits, deductibles, vehicles, drivers, optional benefits, and payment schedule.
This gives you a clean baseline for comparison.
2. Get comparable quotes
Use the same drivers, vehicles, limits, deductibles, and major coverage choices whenever possible.
A lower price may simply reflect lower protection.
3. Check the replacement insurer
Confirm the legal insurer name, state availability, total premium, policy term, fees, claims contact, and payment requirements.
The monthly payment alone does not describe the contract.
4. Buy the new policy
Choose an effective date and time that leaves no interruption after the old coverage ends.
A gap can create legal, lender, registration, and insurance problems.
5. Save proof of insurance
Keep the new ID card, declarations page, policy number, and payment confirmation.
You may need proof for a lender, registration, or cancellation request.
6. Cancel the old policy
Contact the old insurer and request cancellation for the intended date.
Do not assume the new insurer will cancel the old policy for you.
7. Keep the final records
Save written cancellation confirmation, any final bill or refund information, and both policy dates.
These records help resolve later billing or coverage questions.
Compare the Same Coverage Before You Switch
A meaningful comparison uses equivalent coverage as closely as possible. The NAIC Auto Insurance Shopping Tool
encourages consumers to record limits and deductibles for each insurer so quotes can be compared on a consistent basis.
Liability limits Match bodily injury and property damage limits whenever possible.
Collision deductible Compare the same deductible if collision coverage is included.
Comprehensive deductible Use the same deductible when comparing comprehensive coverage.
UM/UIM Check whether uninsured or underinsured motorist coverage is included, optional, or rejected.
Medical coverage Compare PIP or MedPay choices where available or required.
Rental and roadside Compare the actual limits and benefits, not just whether the name appears on the quote.
Policy term Confirm whether each quote covers six months, twelve months, or another term.
Total premium Compare the total policy price, not only the first or monthly payment.
Should You Cancel the Old Policy First?
No. The replacement policy should be in force before the old policy’s cancellation becomes effective.
The NAIC specifically warns consumers changing insurers to avoid an interruption between policies.
If the vehicle is financed, it also recommends notifying the lender and providing proof of the new coverage.
Avoid a lapse: Confirm the replacement policy’s effective date and time,
save proof of insurance, and then request cancellation of the old policy for the appropriate date.
Can You Receive a Refund After Canceling?
Possibly. The NAIC says an insurer may refund part of the premium when a policy is canceled before its normal
expiration date. The amount and timing can depend on the insurer, state rules, cancellation date,
amounts still owed, and the terms of the policy.
Questions for the current insurer
What date and time will the cancellation take effect?
Is written or signed notice required?
Is any unused premium refundable?
How will the refund be calculated?
Are any balances or charges still due?
How and when will the final statement or refund be sent?
Will automatic payments stop automatically after cancellation?
Financed or Leased Vehicles Need Extra Attention
Do not reduce physical-damage coverage on a financed or leased vehicle without checking the contract.
Lenders commonly require insurance protecting their interest in the vehicle, and the NAIC recommends
notifying the lender when insurance companies change and providing proof of replacement coverage.
If required coverage lapses, a lender may have remedies under the finance agreement, including lender-placed
insurance in some situations. The replacement policy should therefore satisfy both state requirements
and any contractual lender or lease requirements.
Ways to Lower the Cost Without Cutting the Wrong Coverage
Triple-I recommends shopping around, checking insurance costs before buying a vehicle,
considering higher deductibles you could actually afford, looking at whether collision or comprehensive
still makes economic sense on an older vehicle, and asking about applicable discounts.
Triple-I also recommends obtaining at least three price quotes when shopping around.
The lowest premium is not automatically the best choice if the coverage or insurer service differs materially.
Cost changes worth testing
Different collision and comprehensive deductibles
Available multi-policy or multi-vehicle discounts
Low-mileage or usage-based options where offered
Coverage on an older paid-off vehicle
Equivalent quotes from multiple insurers
Changes that need more caution
Lower liability limits
Removing collision or comprehensive from a financed vehicle
Dropping UM/UIM or medical coverage without checking state rules
Choosing a deductible you could not afford after a loss
Canceling before replacement coverage is active
Estimate Different Coverage Choices Before You Commit
If you are still deciding how much of the premium comes from the vehicle, deductible, or coverage level,
you can
estimate car insurance costs at different coverage levels
before requesting final quotes. Treat the result as a planning estimate rather than an insurer-approved premium.
Drivers whose main concern is affordability can also compare
lower-cost car insurance options
without assuming that the lowest monthly payment is automatically the safest policy choice.
What to Do After the New Policy Starts
After-switch checklist
Confirm the replacement policy number, effective date, and effective time.
Save the new insurance ID card and declarations page.
Update proof of insurance kept in the vehicle or mobile wallet.
Notify the lender or leasing company when required.
Cancel the old policy for the intended date only after the replacement coverage is confirmed.
Save written cancellation confirmation from the old insurer.
Check for any final bill, refund, or automatic-payment activity.
Common Problems to Avoid
Canceling too early A quote or application is not proof that replacement coverage is active.
Comparing different limits Lower limits can make one quote appear cheaper than another.
Ignoring deductibles A lower premium may come with much higher out-of-pocket claim costs.
Missing lender requirements Financed or leased vehicles can have contractual insurance requirements.
Comparing only monthly payments Down payments, fees, policy terms, and total premiums can differ.
Not keeping cancellation proof Written records help if billing continues after the intended cancellation date.
Leaving autopay unchecked Verify that recurring payments are handled correctly after cancellation.
Frequently Asked Questions About Switching Car Insurance
Can I switch car insurance before the policy expires?
Yes. The NAIC consumer guide states that a policyholder can cancel an auto policy before its normal expiration date.
Check the insurer’s cancellation process and your state’s rules before doing so.
Should I cancel the old policy before buying the new one?
No. Confirm that the replacement coverage is active and save proof of insurance before the old policy’s cancellation takes effect.
Will I receive a refund after canceling?
You may. The NAIC says an insurer may refund part of the premium after a cancellation.
The amount and timing depend on the policy, insurer, state rules, and any remaining balance.
Does switching insurers automatically lower the premium?
No. Insurers use different rating methods, but the final price also depends on driver, vehicle,
location, coverage, deductible, eligibility, and other rating factors.
How many quotes should I compare?
Triple-I recommends getting at least three price quotes when shopping around.
Compare equivalent coverage and the total premium rather than price alone.
What should I keep after switching?
Keep the new policy documents and proof of insurance, plus written confirmation showing when the old policy was canceled
and any final bill or refund information.
Compare Before You Switch
Compare Auto Insurance Quotes by ZIP Code
Enter your ZIP code to compare auto insurance quote options before switching.
Check equivalent limits, deductibles, total premiums, and policy terms before canceling existing coverage.
Confirm the replacement policy first, then cancel the old policy for the correct date.
Sources
This article uses consumer insurance resources from the NAIC and Triple-I.
Cancellation rules, refunds, notice requirements, pricing, lender requirements, and policy terms can vary,
so confirm time-sensitive details with the current and replacement insurers and, when applicable, the lender.
Editorially maintained information about Fred Loya claims, accident reporting, and auto insurance coverage.
Created: December 16, 2013
Updated: September 12, 2026
Fred Loya Claims
Accident Reporting
Claim Coverage
The LoyalInsurance.org Editorial Team maintains consumer-focused information about claim reporting,
policy coverage, deductibles, accident documentation, repair questions, and insurance shopping topics.
LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance
or any insurer. Claim decisions depend on the policy, coverage in force, exclusions, deductibles,
state rules, and the facts of the loss.
Fred Loya Claims
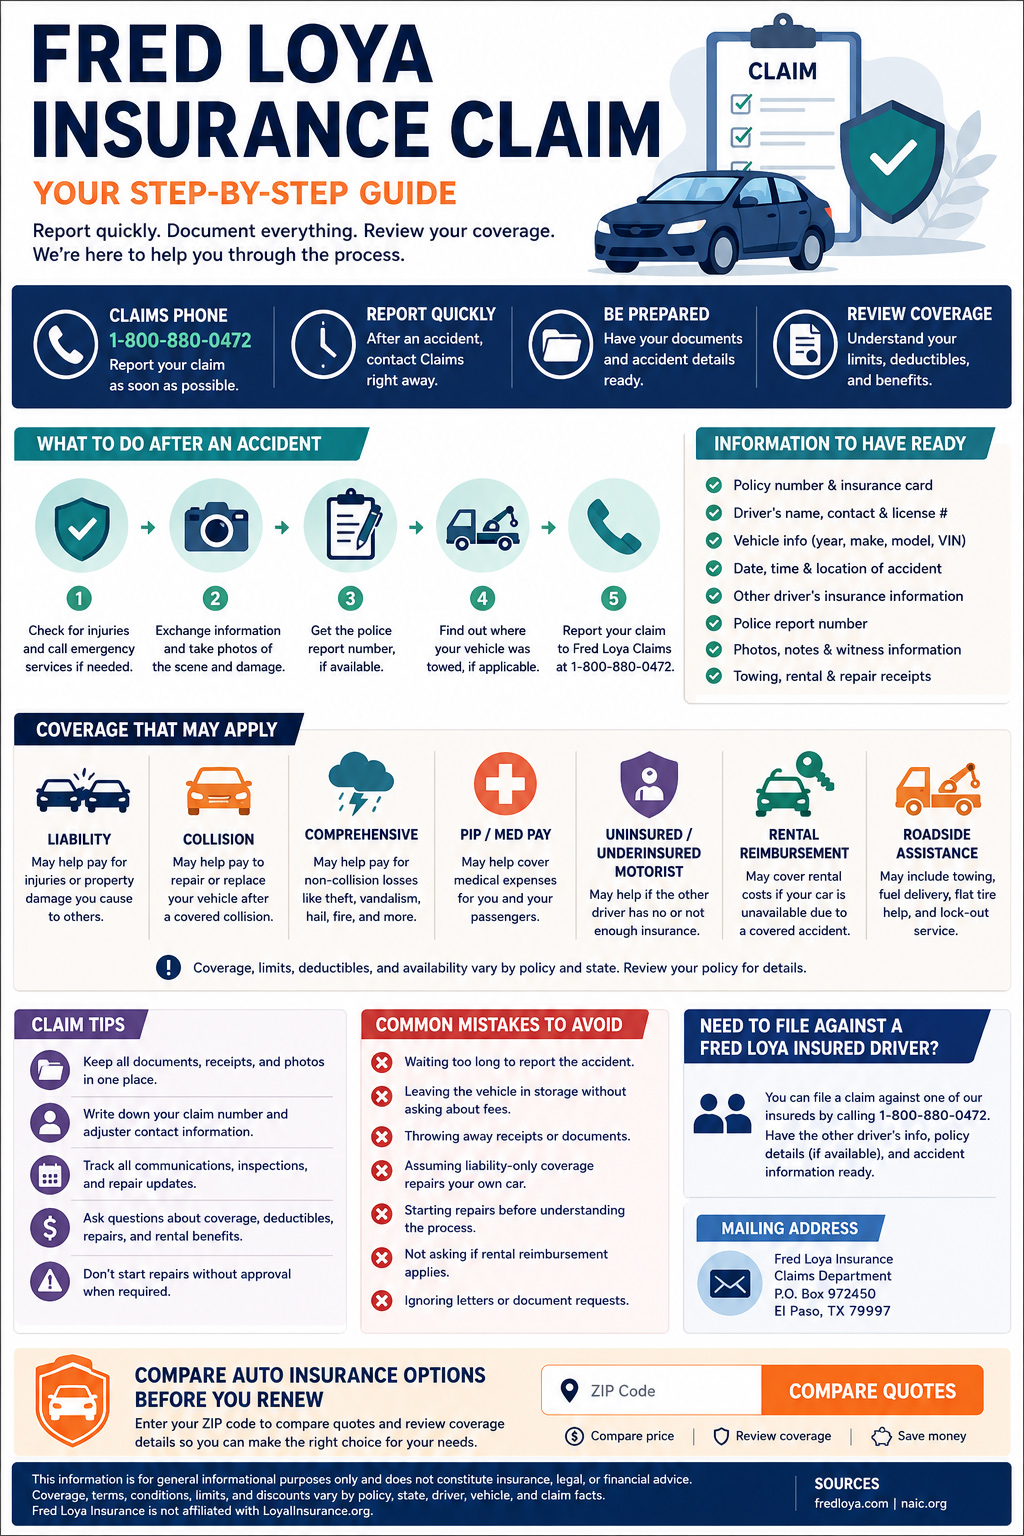
A Fred Loya insurance claim can be reported at
1-800-880-0472. Fred Loya says claims should be reported as soon as possible
after an accident, with accident information ready when you call.
The company’s
official claims page
also tells drivers to protect the vehicle from additional damage, find out where it was taken if it was towed,
and keep documents such as police reports and accident exchange information together.
Claims number1-800-880-0472
ReportAs soon as possible
Have readyAccident information
KeepPhotos and documents
Fred Loya Claims Phone Number and Hours
Fred Loya currently lists 1-800-880-0472 for reporting an auto insurance claim.
Its claims page lists claim-reporting hours as Monday through Friday, 8:00 a.m. to 7:00 p.m. MST,
and Saturday, 8:00 a.m. to 4:00 p.m. MST.[1]
The same number can be used to file a claim on your own policy or against a Fred Loya insured driver.
Fred Loya asks callers to have accident information readily available.[2]
How the Fred Loya Claim Process Works
Fred Loya’s current claims page describes a five-part process after the loss is reported:
the policy and coverage are checked, accident details are gathered, vehicle damage is estimated,
additional evidence is collected when needed, and the claim reaches a final disposition based on
the information gathered during the liability investigation.[1]
The company states that a liability claims adjuster will be assigned to the loss report and contact
the claimant within 24 hours. The adjuster may obtain statements from the parties, photos, estimates,
police reports, witness information, scene evidence, and applicable traffic-law information as part of the investigation.
Coverage is not automatic: Reporting a claim starts the claim process, but it does not guarantee
that every loss or expense is covered. The policy, coverage in force, exclusions, deductibles, limits,
driver status, payment status, and facts of the loss can affect the outcome.
What to Do After an Accident
Fred Loya’s own accident instructions emphasize four immediate tasks: report the claim,
protect the vehicle from additional damage, locate the vehicle if it was towed, and create a file
containing documents related to the loss.[3]
Accident information worth keeping together
Insurance and driver information exchanged at the scene
Photos of vehicle damage and the accident scene
Police report or accident exchange information
Towing company and storage-yard information
Repair estimates and inspection information
Rental, towing, storage, and other claim-related receipts
Claim number and assigned adjuster contact information
Emails, letters, and notes from claim-related calls
Information to Have Ready When You File
Fred Loya’s FAQ specifically asks callers to have all accident information readily available.
Having the basic policy, vehicle, driver, and loss details together can reduce unnecessary follow-up.
Policy information Policy number, named insured, insurance card, and effective dates.
Driver details Names, phone numbers, license information, and addresses for involved drivers.
Vehicle details Year, make, model, license plate, VIN, and current vehicle location.
Accident facts Date, time, location, and a factual description of what happened.
Other party information Insurance information, vehicle details, and contact information when available.
Police information Report number and responding agency when a report was made.
Photos and documents Scene photos, damage photos, accident exchange forms, and towing documents.
Expenses Receipts for towing, storage, rental, and other claim-related costs.
What Coverage May Apply?
The type of coverage that matters depends on the loss and the policy. Current Fred Loya materials describe
liability, collision, comprehensive, medical payments, personal injury protection, rental reimbursement,
and roadside assistance among its auto insurance categories. The NAIC also explains that auto policies can
combine required and optional coverage differently by state and policy.[4][5]
Coverage
When It May Matter
What to Check
Liability
A covered accident causes injury or property damage to another person.
Check the bodily injury and property damage limits and applicable exclusions.
Collision
Your insured vehicle is damaged in a covered collision.
Confirm that collision is included and which deductible applies.
Comprehensive
The vehicle has a covered non-collision loss such as theft, hail, fire, flood, vandalism, or animal impact.
Check the deductible, exclusions, and covered causes of loss.
Medical or PIP
Medical expenses or other covered injury-related costs arise after an accident.
Availability, requirements, limits, and benefits depend on the state and policy.
Uninsured/underinsured motorist
The other driver has no insurance or insufficient insurance and the applicable coverage responds.
Check whether the coverage exists on the policy and what limits or state rules apply.
Rental reimbursement
Your vehicle is being repaired after a covered accident and the rental benefit applies.
Confirm the benefit, limits, qualifying circumstances, and any authorization requirements.
If an accident exposes a limit, deductible, or missing protection that you had not considered before,
the question of
how much auto insurance coverage fits your situation
becomes especially relevant before the next renewal.
Liability Claims vs. Damage to Your Own Vehicle
Liability coverage and physical-damage coverage serve different purposes. Liability generally addresses
covered injuries or property damage caused to others. Damage to your own vehicle usually requires the
applicable collision or comprehensive coverage, subject to the policy and deductible.
A policy that contains only liability coverage should not be assumed to pay for repairs to your own vehicle.
Check the declarations page before making assumptions about what the policy includes.
What If the Vehicle Was Towed?
Fred Loya specifically tells drivers to find out where the vehicle was taken if it was towed.
That information can be important because the adjuster may need the storage location and access information,
while towing and storage charges can continue to accumulate.[3]
Keep these towing details
Towing company name and phone number
Storage-yard address
Date the vehicle was towed
Police or tow-report number when available
Current storage charges and release requirements
Towing and storage receipts
Rental Reimbursement and Roadside Assistance Are Different
Fred Loya currently describes rental reimbursement as coverage that can pay for a rental car while an insured
vehicle is repaired after a covered accident when the vehicle is unavailable for more than 24 hours.
Whether it applies to a particular loss depends on the policy and claim.[6]
Roadside assistance is described separately for non-accident vehicle damage or breakdowns and can include
towing to the nearest repair facility, flat-tire assistance, fuel delivery, and lock-out service.
It should not automatically be treated as accident-claim towing coverage.
Filing Against a Fred Loya Insured Driver
You do not need to be a Fred Loya customer to report a claim against one of its insured drivers.
The company’s FAQ directs both policyholders and people filing against one of its insureds to the same
Claims Department number, 1-800-880-0472.[2]
Fred Loya’s published claim process says the adjuster gathers statements and other evidence, evaluates
policy coverage and accident facts, prepares or obtains damage information, and reaches a final claim disposition
based on the investigation.
How to Check a Fred Loya Claim Status
Fred Loya says claim-status questions can be directed to 1-800-880-0472 during its listed claims hours.
Once the claim has been filed and an adjuster assigned, the company says you can contact that adjuster directly
for questions or to provide and obtain information needed to move the claim forward.[1]
Claim number Keep it available whenever you call or send documents.
Adjuster Save the adjuster’s direct contact information once assigned.
Timeline Record calls, inspections, document requests, and repair updates.
Documents Keep police reports, estimates, receipts, photos, and letters together.
Open requests Note anything the adjuster still needs from you.
Next contact Ask when you should expect the next update if no date has been provided.
When Payment Status and a Claim Overlap
A claim and a billing issue are separate questions. A payment receipt does not by itself establish that a particular
loss is covered, and a claim report does not resolve an overdue premium or cancellation issue.
If the accident occurred close to a due date or cancellation notice, check the policy documents and the
Fred Loya payment deadlines and account tools
so you have the billing record, receipt, and policy-status information available when speaking with the insurer.
Common Claim Problems to Avoid
Keep the process documented
Do not delay reporting the accident unnecessarily.
Do not lose track of where a towed vehicle is being stored.
Keep receipts, estimates, photos, and claim correspondence.
Do not assume liability coverage repairs your own vehicle.
Confirm the applicable deductible before making financial assumptions.
Ask whether rental reimbursement applies before relying on a rental benefit.
Respond to reasonable document and information requests from the assigned claims representative.
What If You Are Unhappy With the Claim Experience?
Start by asking which policy term, coverage limit, deductible, exclusion, or claim fact affected the decision.
Keep the response and supporting correspondence with the rest of your claim file.
If the experience leads you to change insurers, arrange the replacement policy before canceling the current one.
The steps for
switching car insurance without creating a coverage gap
matter because even a short lapse can leave you uninsured and may affect future pricing.
After the claim: Check your declarations page again and note the liability limits,
collision and comprehensive deductibles, rental reimbursement, uninsured/underinsured motorist coverage,
excluded drivers, vehicle information, and any coverage that did not work the way you expected.
Frequently Asked Questions About Fred Loya Insurance Claims
What is the Fred Loya claims phone number?
Fred Loya currently lists 1-800-880-0472 for filing an auto insurance claim.
When should I report a Fred Loya claim?
Fred Loya says a claim should be reported as soon as possible after an accident occurs.
Can I file against a Fred Loya insured driver?
Yes. Fred Loya’s FAQ says its Claims Department handles claims filed on your own policy
or against one of its insureds.
How do I check my claim status?
Fred Loya directs claim-status questions to 1-800-880-0472 during its claims hours.
After an adjuster is assigned, the company says you can contact that adjuster directly for claim-related questions.
Does reporting a claim mean the damage is covered?
No. Reporting starts the process. Coverage still depends on the policy, coverage in force,
limits, deductibles, exclusions, and the facts of the loss.
Does liability-only insurance repair my own vehicle?
Liability generally addresses covered injury or property damage caused to others.
Damage to your own vehicle ordinarily requires applicable physical-damage coverage such as collision
or comprehensive, depending on the type of loss and policy terms.
Review Your Options
Compare Auto Insurance Options After a Claim
Enter your ZIP code to compare auto insurance quote options and check coverage details before choosing or renewing a policy.
Compare price, liability limits, deductibles, rental benefits, and policy terms before choosing coverage.
Sources
This article uses current Fred Loya public claim information and consumer auto-insurance resources.
Claim instructions, hours, policy terms, coverage, and benefits can change, so confirm time-sensitive
information with the insurer and the policy documents.
Editorially maintained information about Fred Loya offices, local support, and auto insurance access.
Created: December 16, 2013
Updated: September 12, 2026
Fred Loya Locations
Car Insurance Offices
Local Insurance Support
The LoyalInsurance.org Editorial Team maintains consumer-focused information about auto insurance companies,
office access, coverage, payments, claims contacts, and practical shopping questions for U.S. drivers.
LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance
or any insurer. Office availability, services, policy terms, pricing, and coverage can vary by state,
location, policy, and customer situation.
Fred Loya Office Locations
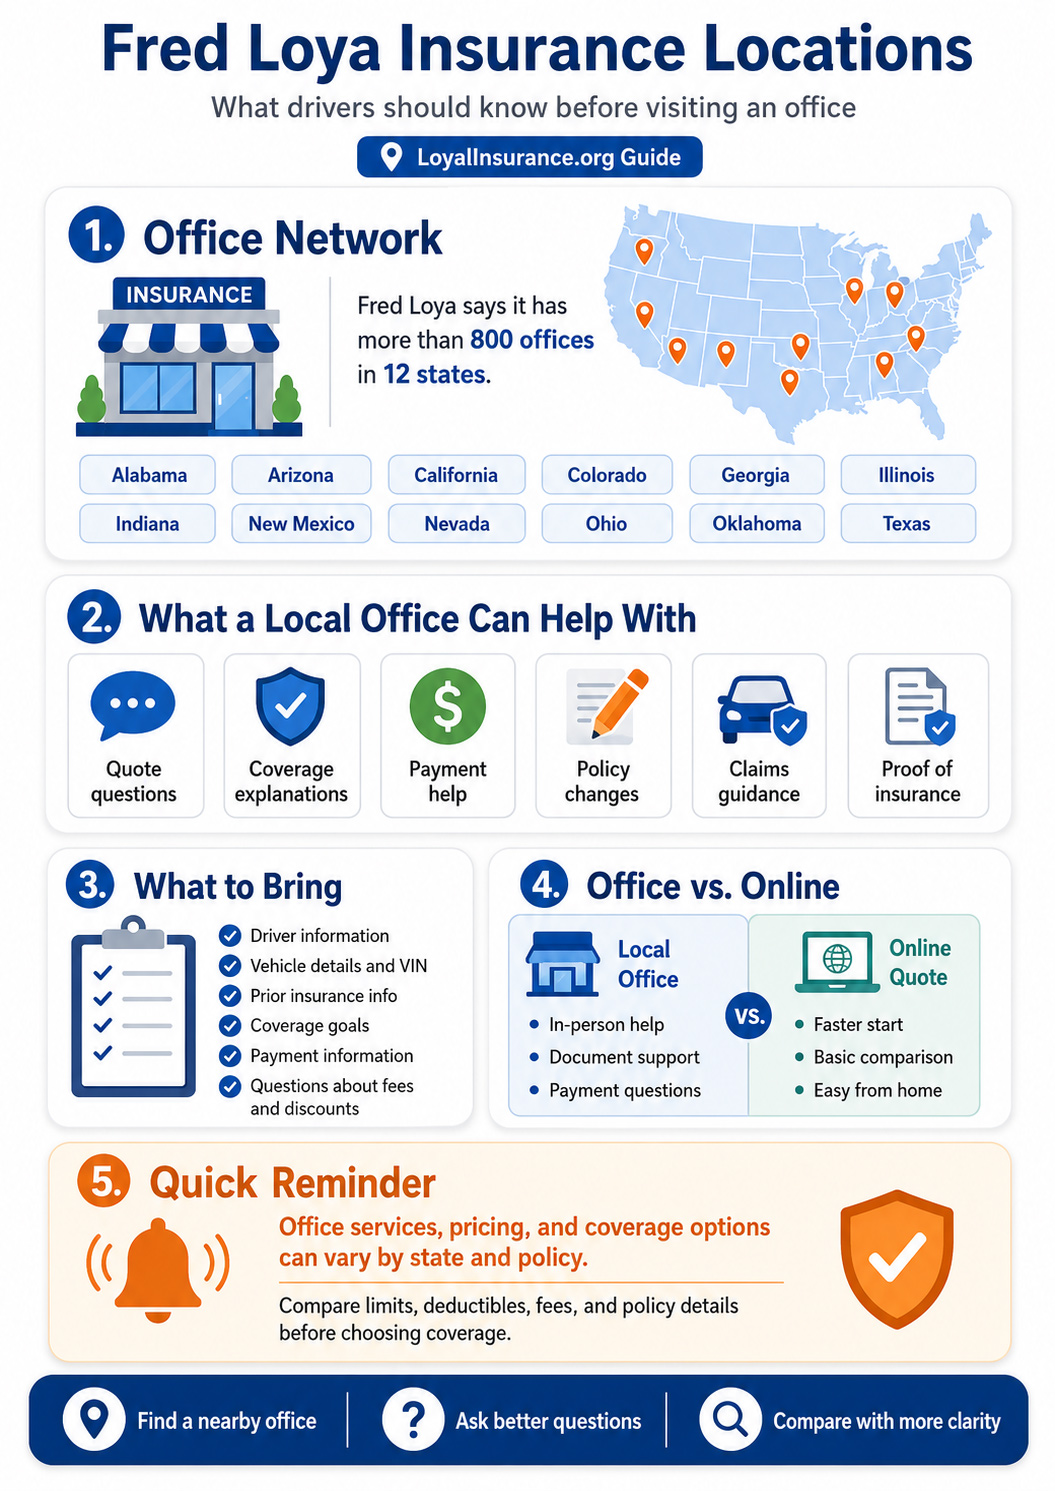
Drivers looking for Fred Loya Insurance locations can search the company’s current office
network by ZIP code, city, or state. Fred Loya says it operates more than 800 offices across 12 states,
and individual listings can show the local address, phone number, opening hours, languages, quote access,
and directions.
The fastest way to confirm a branch is to use the
official Fred Loya location finder
before leaving home. Office hours and available services can differ, so call the listed branch when your visit
involves a policy change, documents, billing, or another time-sensitive request.
How Many Fred Loya Insurance Locations Are There?
Fred Loya currently states that it has more than 800 offices in 12 states:
Alabama, Arizona, California, Colorado, Georgia, Illinois, Indiana, New Mexico,
Nevada, Ohio, Oklahoma, and Texas.
Some official location listings appear under the Fred Loya Insurance name while others can display
Loya Insurance Company. The relationship between those names is covered in our
Loya Insurance Company overview,
while the insurer name on your own policy documents remains the one that matters for your coverage.
States listed by Fred Loya
Alabama
Arizona
California
Colorado
Georgia
Illinois
Indiana
New Mexico
Nevada
Ohio
Oklahoma
Texas
What the Official Location Finder Shows
Fred Loya’s location finder lets users search by ZIP code or city and also browse by state.
Current listings can include the office name, street address, local phone number, opening hours,
languages, a quote option, and directions.
Those details are more useful than relying on an old directory entry because branch hours,
phone numbers, and office availability can change. Confirm the live listing before making a trip.
Fred Loya office network, states served, information to bring, and details to confirm before visiting a branch.
When a Local Office May Be Useful
A local branch can be useful when a request needs a signature, in-person documentation,
or direct help with a policy question. Fred Loya’s current FAQ says some personal-information changes
may be handled by phone, while others require a signature and must be completed at a local branch.
A branch may be useful for
Starting or discussing an auto insurance quote
Questions about available coverage
Policy changes that require a signature
Help identifying the correct policy-service channel
Questions about proof-of-insurance documents
Confirming branch-specific services before a visit
Online or phone access may be faster for
Starting a quote
Making an online payment
Accessing an online account
Printing available ID cards or declarations
Calling customer service
Reporting a claim through the claims channel
What to Confirm Before Visiting
Not every branch should be assumed to handle every request. The safest approach is to call the specific office
shown in the official finder and ask whether it can handle the reason for your visit.
Before You Go
Why It Matters
Address and hours
Branches can have different schedules, including different Saturday hours.
Local phone number
Calling first can prevent a trip if the office cannot handle the specific request.
Language availability
Current listings may identify languages available at a particular office.
Documents required
Policy changes, quotes, or other service requests may require identification or policy information.
Service needed
Claims, roadside assistance, online payments, and some policy-service requests may use separate channels.
What to Bring for a Quote
Fred Loya currently asks customers seeking a quote to have their current insurance policy information,
current vehicle and driving-record information, the driver’s license number for each driver,
and the vehicle identification number (VIN) ready.
Current policy information Bring existing coverage details if you already have insurance.
Vehicle information Have the VIN and current vehicle details available.
Driving information Be prepared to provide current driving-record information.
Driver licenses Have the license number for each driver who may need to be listed.
Coverage questions Write down limits, deductibles, and optional protections you want to compare.
Final price questions Ask about the first payment, recurring payments, fees, and effective date.
Coverage Questions Worth Asking at the Office
Fred Loya’s current website lists liability, comprehensive, collision, medical coverage,
personal injury protection, rental reimbursement, and roadside assistance among its auto insurance categories.
Exact availability and policy terms can depend on the state and policy.
Policy details to confirm
Liability limits: the limits that apply to covered bodily injury and property damage.
Collision deductible: the amount that may apply when collision coverage responds.
Comprehensive deductible: the amount that may apply to covered non-collision losses.
Medical or PIP coverage: availability and requirements can vary by state.
Rental reimbursement: confirm when the benefit applies and any applicable limits.
Roadside assistance: confirm whether it is included or optional and what services are covered.
If roadside coverage is part of the policy, the
Fred Loya roadside assistance details
cover towing, flat-tire help, fuel delivery, lock-out service, and the current 24-hour assistance number.
Minimum Insurance Requirements Vary by State
Auto insurance requirements are set by state law. The NAIC notes that most states require at least a basic
level of auto coverage, while many drivers choose limits or protections above the legal minimum.
A state-minimum policy can satisfy a legal requirement without necessarily providing enough protection
for a serious loss. The tradeoffs behind
basic car insurance coverage
become especially important when comparing liability limits, deductibles, and the amount of financial risk
you would keep yourself.
Important: Minimum legal requirements are not a recommendation for every driver.
Check the limits on the actual quote and consider lender or lease requirements, vehicle value,
assets, deductibles, and your ability to absorb an uninsured loss.
Online, Phone, or Local Office?
The best service channel depends on the task. The official website offers online quote access,
online payment, account login, and a location finder, while customer service and claims have separate phone channels.
Option
Useful For
What to Keep in Mind
Online
Starting a quote, paying online, account access, and searching for offices.
Use the current insurer website rather than an old directory or saved link.
Phone
Customer service, quote questions, and determining whether a branch visit is necessary.
Claims use a separate claims channel from general customer service.
Local office
In-person quote discussions and service requests that require a branch or signature.
Call first because services and hours can vary by location.
Credit Information and Quote Pricing
Fred Loya’s current FAQ says competitive rates are available with and without a credit score
and that multiple products are available. It directs customers to a local office for details.
That does not mean every quote will be identical or that credit is the only rating factor.
Final pricing can also depend on the information used for the quote, the vehicle, driving history,
coverage selected, state rules, discounts, eligibility, and other underwriting factors.
Ask what changed if a quoted price changes after additional information is provided.
How to Compare the Office Experience With the Policy
A nearby branch can be convenient, but convenience should not outweigh the actual contract.
Compare the limits, deductibles, optional benefits, payment terms, exclusions, and claims process
before deciding whether a policy fits your needs.
Service history can also help you prepare better questions. Our
Fred Loya insurance review
focuses on company experience, complaints, policy-service considerations, and factors worth checking
before relying on a quote or office interaction.
Questions to ask before buying
Which legal insurer will issue the policy?
What liability limits are included?
Which deductibles apply?
Are collision and comprehensive included?
Which optional benefits are included or available?
What is the total policy cost and payment schedule?
When does coverage become effective?
How are claims and policy changes handled?
Frequently Asked Questions About Fred Loya Insurance Locations
How do I find a Fred Loya Insurance office?
Use Fred Loya’s official location finder and search by ZIP code or city, or browse by state.
Confirm the address, local phone number, and opening hours before visiting.
How many states have Fred Loya offices?
Fred Loya currently describes its office network as more than 800 offices across 12 states:
Alabama, Arizona, California, Colorado, Georgia, Illinois, Indiana, New Mexico,
Nevada, Ohio, Oklahoma, and Texas.
Do all Fred Loya offices have the same hours?
No assumption should be made that every branch follows the same schedule.
The official finder publishes hours for individual locations, so check the specific office before visiting.
Can policy changes require a local branch?
Yes. Fred Loya’s FAQ says some personal-information changes may be handled by phone,
while other changes require a signature and must be completed in person at a local branch.
Can I manage policy documents online instead?
Fred Loya’s online account tools list features such as making a payment, printing an ID card,
printing a declaration page, reviewing policy details, and viewing a payment summary.
Ready to Compare?
Compare Auto Insurance Quote Options
Enter your ZIP code to continue comparing auto insurance options and review quote paths
that may fit your coverage needs and budget.
Compare price, coverage limits, deductibles, fees, payment terms, and policy details before choosing auto insurance.
Sources
This article uses current Fred Loya public information and consumer insurance resources.
Office availability, hours, services, policy terms, and coverage can change, so verify
time-sensitive details with the insurer and your policy documents.
Editorially reviewed informational content for U.S. car insurance topics
Created on December 16, 2013, 3:13 AM UTC+0 Last updated on September 12, 2026
Loya Insurance
Company Overview
Auto Insurance
The LoyalInsurance.org Editorial Team creates informational content focused on auto insurance costs, company research, quote comparison, local office support, coverage types, and practical shopping topics for U.S. drivers.
Articles are written to help readers better understand how coverage limits, deductibles, office access, quote tools, claims contacts, payment options, and insurer requirements may affect the process of shopping for car insurance.
This content is for general informational purposes only and does not constitute insurance, legal, or financial advice. Coverage availability, pricing, discounts, fees, claims handling, office services, and policy terms vary by insurer, state, location, vehicle, and driver profile. LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance, Loya Insurance Group, or any insurer.
Company Overview
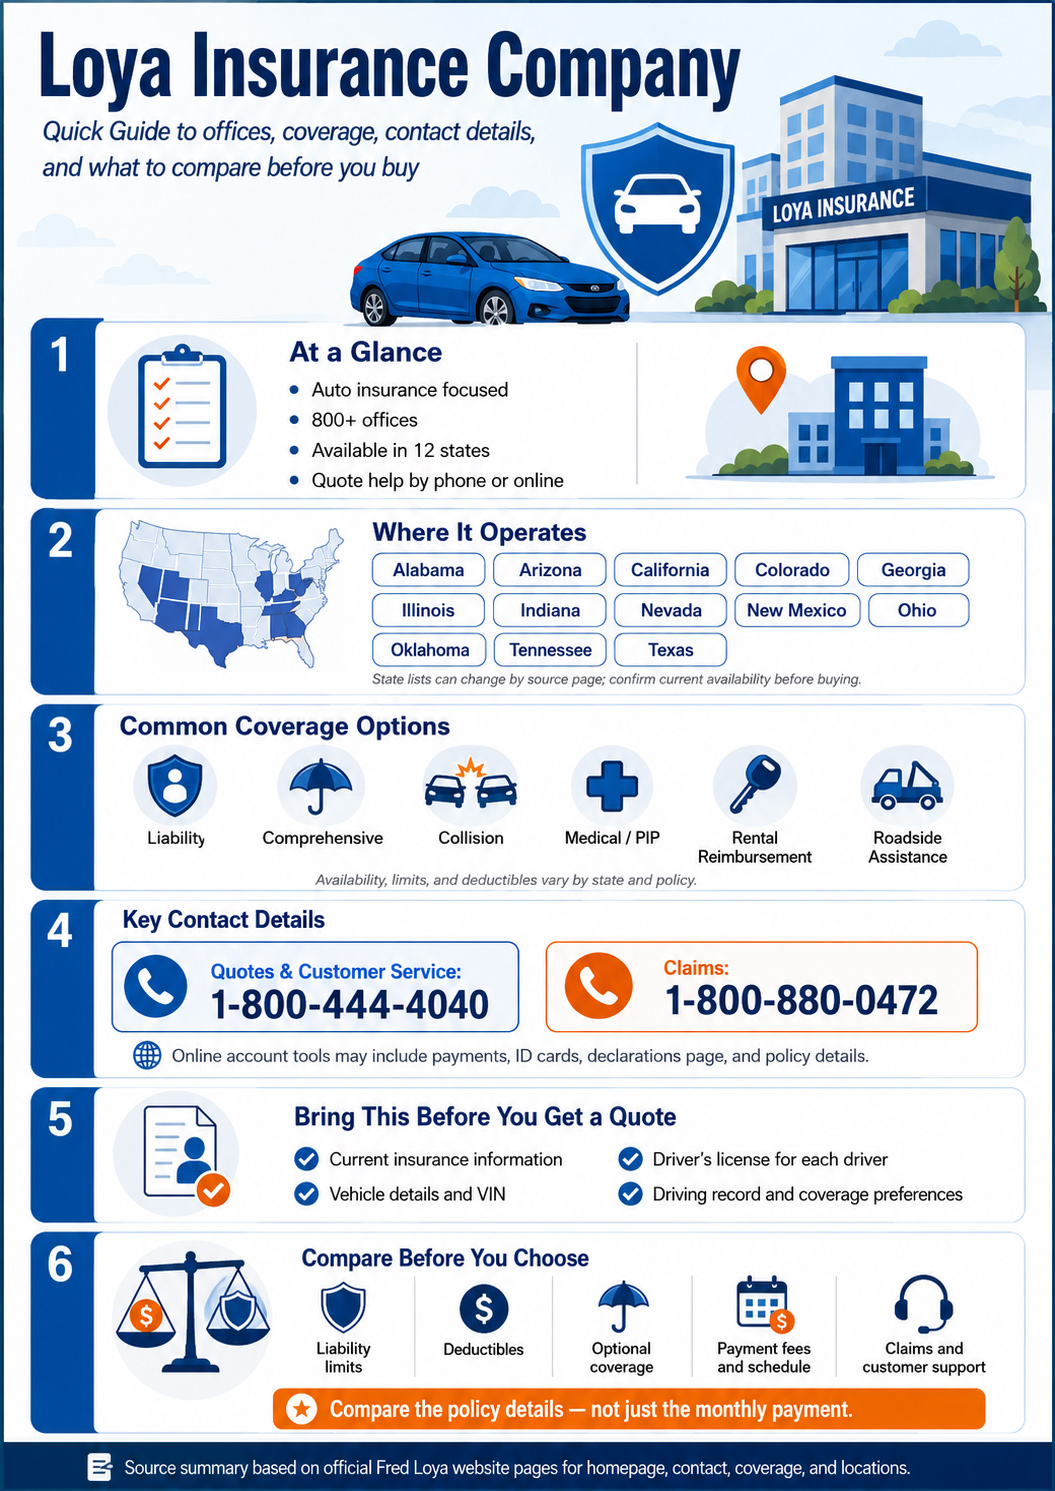
Loya Insurance Company is a legal insurer name used within Loya Insurance Group. Fred Loya’s official claims information identifies Loya Insurance Company, Fred Loya Insurance, and Young America Insurance among the companies whose claims are handled by the group. For consumers, the insurer named on the declarations page and policy documents matters more than the public-facing brand because those documents identify the coverage actually in force.
This page focuses on the company structure, office access, contact options, online tools, quote preparation, and policy basics. More specific questions about payments, claims, local offices, or coverage are linked where they are directly relevant instead of repeated here.
Main focusCompany overview
Useful forNew shoppers
CompareCoverage and price
Before buyingConfirm final terms
Loya Insurance Company, Fred Loya Insurance, and Loya Insurance Group
Fred Loya’s public website uses Fred Loya Insurance branding, while its contact and claims pages also use the Loya Insurance Group name. Its claims page specifically states that the group handles claims for subsidiaries including Loya Insurance Company, Fred Loya Insurance, and Young America Insurance.
These names should not be treated as interchangeable on policy documents. The legal insurer shown on the declarations page, insurance card, bill, claim correspondence, and policy forms is the name that matters for the contract, coverage limits, deductibles, exclusions, and claim instructions.
Important document reminder: Do not rely only on a brand name or office sign. Before buying or renewing, confirm the legal insurer name, policy number, effective date, coverage limits, deductibles, fees, and claims instructions on your own documents.
Why Direct Communication Still Matters
Insurance decisions are easier to start online, but many drivers still benefit from a human explanation. A quote can show a monthly price, but it may not clearly explain what is included, what is excluded, what deductible applies, or how much financial protection the policy actually provides.
Speaking with a local office or representative can help drivers understand liability limits, deductibles, optional coverage, payment schedules, cancellation rules, proof of insurance, and state-specific requirements. This can be especially useful for first-time buyers, drivers with prior coverage gaps, households adding a vehicle, or shoppers comparing minimum coverage with broader protection.
Comparison reminder: Always compare coverage, not just price. A cheaper policy may cost less each month, but it may also include lower limits, fewer protections, stricter payment rules, or higher out-of-pocket costs after a claim.
The Loya Insurance Local Office Model
The Loya insurance model is commonly associated with physical offices and local support. Drivers who prefer in-person help can check current Fred Loya Insurance locations before visiting, then confirm the address, hours, language availability, and services directly with the office.
At the same time, many drivers now begin online because it is faster to request a quote, compare basic price ranges, and prepare questions before calling or visiting an office. The best approach is often a mix: start with the information you can gather online, then confirm final policy details directly before purchasing.
Office support may help with
First-time insurance questions
Coverage explanations
Payment and billing questions
Policy document help
Vehicle or driver changes
Proof of insurance questions
Online access may help with
Starting a quote quickly
Comparing general pricing
Paying online when available
Accessing account tools
Preparing information before a call
Checking general coverage resources
What Drivers Can Do Online or by Phone
Fred Loya’s official website provides access to online quote tools, payment options, account login, coverage information, claims resources, and location search. Customers managing an existing policy will find the Fred Loya Insurance payment options relevant for online payments, due-date details, receipts, ID cards, declaration pages, and account tools.
For quotes and customer service, Fred Loya currently lists 1-800-444-4040. Claims are reported at 1-800-880-0472, while its 24-hour roadside assistance coverage lists 1-855-548-5626. If you need to route a call, the Loya insurance phone numbers and department contacts separate the main support paths.
After an accident, the Fred Loya insurance claim process follows a separate reporting and adjuster workflow from billing or policy-service questions.
Common reasons to contact the company
Requesting a new auto insurance quote
Reviewing coverage options before buying
Making or confirming a payment
Getting proof of insurance or ID cards
Asking about policy changes
Reporting or following up on a claim
Checking roadside assistance details
Finding a nearby office
Office Availability and State Listings Can Change
Fred Loya’s official website describes more than 800 offices and offers a location finder by ZIP code, city, or state. Because office lists, hours, and services can change, drivers should confirm location details directly before visiting.
When using a location finder, check the address, phone number, business hours, language support, parking access, and whether the office can help with the specific issue you have. A nearby office can be convenient, but it is still important to compare policy terms before buying.
Before visiting an office, confirm:
The address and office hours
The local phone number
Whether the office handles quotes, payments, or policy changes
Whether you need an appointment
Which documents to bring
Whether the office can help with your specific policy or claim issue
What to Have Ready Before Requesting a Quote
Preparing your information before requesting a quote can make the process smoother. Fred Loya’s contact page says drivers should have current insurance policy information, current vehicle and driving record information, driver’s license number for each driver, and the vehicle identification number ready when seeking a quote.
ZIP code and address Location can affect availability, pricing, and state-specific requirements.
Driver details Names, dates of birth, license numbers, and household driver information may be needed.
Vehicle information VIN, year, make, model, mileage, ownership, and usage details can affect the quote.
Current insurance Prior insurer, coverage dates, limits, and lapse information may affect eligibility or pricing.
Driving history Accidents, tickets, claims, and violations may affect the quote.
Coverage preferences Liability limits, deductible preferences, and optional coverage choices should be reviewed.
Coverage Terms to Understand Before Buying
Fred Loya’s current website lists liability, comprehensive, collision, medical coverage, personal injury protection, rental reimbursement, and roadside assistance among its auto coverage categories. Details about Loya car insurance coverage and policy options should still be checked against the declarations page and policy forms issued for the specific state and policy.
Fred Loya’s FAQ also states that there is no single policy that provides “full coverage”; every policy has limits, deductibles, and exclusions. Before accepting a policy, focus on what is included, what is excluded, the applicable limits and deductibles, and how a covered claim would be handled.
Term
Simple Meaning
Why It Matters
Policy
The contract that explains your coverage.
The policy documents control what is covered and excluded.
Premium
The price you pay for insurance.
Compare the full policy cost, not only the first payment.
Deductible
The amount you may pay out of pocket for certain claims.
A higher deductible may lower the premium but can increase claim-time costs.
Limits
The maximum amount a policy may pay for specific coverage.
Low limits can leave you exposed after a serious accident.
Exclusions
Situations or uses the policy does not cover.
Exclusions can matter for household drivers, business use, rideshare use, or excluded drivers.
Use this visual checklist to compare office access, contact details, coverage options, quote preparation steps, deductibles, payment fees, and policy terms before choosing auto insurance.
How Drivers Should Compare Auto Insurance
Before choosing a policy, compare more than the advertised price. The right policy depends on the vehicle, driving history, location, coverage needs, state requirements, lender or lease rules, and the amount of financial risk the driver is willing to keep.
A fair comparison uses the same driver details, vehicles, coverage limits, deductibles, and optional coverages whenever possible. If one quote is cheaper, ask whether it has lower liability limits, a higher deductible, fewer optional benefits, a different policy term, or additional fees.
Compare by cost
First payment
Monthly payment
Total policy cost
Installment fees
Cancellation fees
Reinstatement rules
Compare by protection
Liability limits
Collision deductible
Comprehensive deductible
Uninsured motorist coverage
Medical coverage options
Roadside or rental options
Application Process: What to Review Before Accepting a Policy
The application process usually begins with basic information about the driver, vehicle, location, and coverage needs. A driver may be asked for ZIP code, vehicle details, current insurance status, driving history, listed drivers, and preferred coverage level.
After a quote is generated, the most important step is review. Drivers should look at liability limits, deductibles, optional protections, total monthly cost, total policy cost, fees, payment schedule, exclusions, and effective date. This helps avoid choosing a policy that looks affordable at first but does not provide the protection expected.
Before accepting a quote, confirm:
The legal insurer name
The policy term and effective date
The listed drivers and covered vehicles
The liability limits and deductibles
Whether collision and comprehensive are included or excluded
Whether roadside, rental, PIP, MedPay, or UM/UIM options are included
The total cost, first payment, installment fees, and cancellation rules
How to get ID cards or proof of insurance
When This Overview Is Most Useful
This Loya Insurance Company overview is most useful when you are early in the research process. It can help you understand the general model before you decide whether to request a quote, call customer service, visit a location, or compare another insurer.
For detailed pricing questions, compare the actual quote and confirm all final terms directly. For local office questions, verify the address, hours, and services through the official location finder. For policy questions, rely on the declarations page and policy forms issued for your coverage.
Best next step: Use this page to understand the company model, then compare actual policy documents before buying. The final decision should depend on coverage, limits, deductibles, fees, claims support, payment terms, and your own risk level.
Frequently Asked Questions About Loya Insurance Company
Is LoyalInsurance.org affiliated with Fred Loya Insurance?
No. LoyalInsurance.org is an independent informational website. It is not affiliated with Fred Loya Insurance, Loya Insurance Group, or any insurer. Drivers should confirm final rates, terms, and coverage directly with the insurer, agent, or quote provider.
What can drivers do through Loya or Fred Loya online tools?
The official Fred Loya website provides access to online quote tools, payment options, account login, coverage information, claims resources, and location search. Availability and exact features can vary, so drivers should confirm directly through the official site or their policy documents.
What should I prepare before requesting a quote?
Have your ZIP code, driver’s license information, vehicle identification number, current insurance details, driving record information, and preferred coverage choices ready. This can make the quote process easier and reduce mistakes.
Should I choose a policy only because there is a local office nearby?
No. A local office can be helpful, but the policy details matter more. Compare coverage limits, deductibles, optional coverages, payment fees, cancellation rules, claims process, and final premium before buying.
What is the difference between a quote and a final policy?
A quote is an estimated offer based on the information provided. The final policy may depend on verification, eligibility, payment, state rules, driver details, vehicle details, discounts, and policy documents.
Compare Options
Compare Auto Insurance Quote Options
Enter your ZIP code to start comparing auto insurance options and review quote paths that may fit your coverage needs and budget.
Compare price, coverage limits, deductibles, fees, payment terms, and policy details before choosing auto insurance.
Sources
This article uses current Fred Loya public information for company contacts, locations, claims, quote preparation, and coverage categories, together with consumer insurance resources from the NAIC and Triple-I. Policy terms, office availability, contact paths, and coverage options can change, so time-sensitive details should be confirmed with the insurer and the policy documents.