Low income car insurance is not one standard insurance product. For most drivers, the goal is to find the lowest sustainable cost while still meeting state requirements and keeping enough protection for the risks they cannot afford to absorb themselves.
The best starting point is to compare equivalent quotes, check official state resources, and separate the monthly payment from the actual policy. Liability limits, deductibles, optional coverage, installment charges, eligibility rules, and the vehicle itself can all change the total cost.
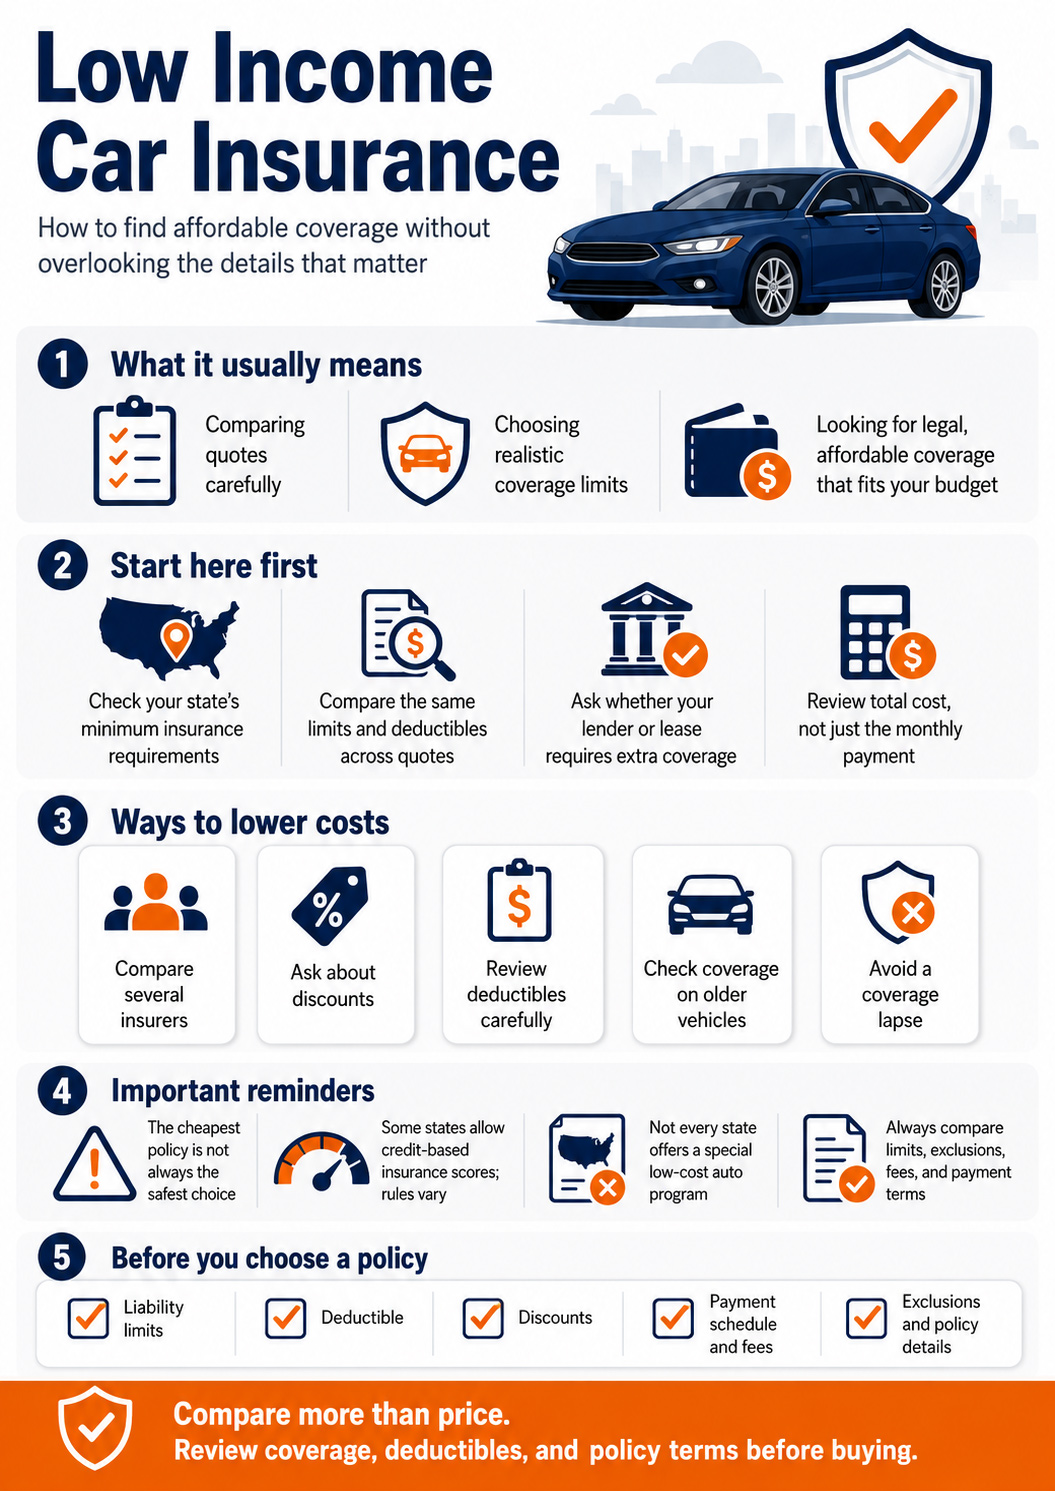
Low Income Car Insurance vs. Minimum Coverage
“Low income” describes a household’s financial situation, not a standard insurance coverage level. “Minimum coverage” refers to the insurance or financial-responsibility rules that apply in a particular state. A low-income household may choose minimum coverage for affordability, but the two terms are not interchangeable.
If you are starting with the lowest legal option, the tradeoffs behind basic auto liability coverage matter because a lower premium can also mean lower liability limits or no physical-damage protection for your own vehicle.
Minimum does not mean sufficient: A policy can satisfy a legal requirement and still leave substantial costs above the liability limit. Compare the actual dollar limits and exclusions before buying.
Check for an Official State Low-Cost Program
Some states offer special mechanisms or assistance programs, but there is no single nationwide “low income car insurance” program. Start with your state insurance department rather than a commercial page that merely uses the phrase “low income.”
California is a clear example. The California Low Cost Automobile Insurance Program (CLCA) was created for income-eligible drivers who need liability insurance to meet the state’s financial-responsibility requirements. The California Department of Insurance directs consumers to the program and currently lists 1-866-602-8861 for eligibility and certified-agent information.
California Low Cost Auto Insurance: Key Rules
California’s current consumer materials say CLCA applicants generally must have household income at or below 250% of the federal poverty level, a valid California driver’s license, be at least 16, own a vehicle worth $25,000 or less, and meet the program’s good-driver requirements or qualify as a new driver. Applicants under 18 must be legally emancipated. Current eligibility should still be checked directly because income thresholds and program rules can be updated.
The CLCA liability limits are $10,000 for bodily injury or death to one person, $20,000 per accident for bodily injury or death to more than one person, and $3,000 for property damage. California’s standard private-passenger minimum limits increased to 30/60/15 in 2025, but the state says the CLCA limits remain unchanged and still satisfy the program’s financial-responsibility requirements.
Before applying to any assistance program
- Confirm the program on an official state insurance-department website.
- Check current household-income eligibility.
- Check driver-license and vehicle requirements.
- Read the liability limits and optional coverage carefully.
- Confirm the current premium or county-based rate directly with the program.
- Do not assume a state program is available outside the state that sponsors it.
Credit-Based Insurance Scores Can Affect Affordability in Some States
A credit-based insurance score is not the same as a traditional lending credit score. The NAIC says insurers often use credit information in underwriting or rating where state law allows it, while state laws place restrictions on how that information can be used.
The NAIC also notes that, in most states, a credit-based insurance score cannot be the sole reason to increase rates or deny, cancel, or refuse to renew a policy. Some states impose stronger restrictions or prohibit certain uses, so check the rule that applies where the vehicle is insured.
If credit information affected the decision: review any adverse-action notice, check the underlying credit report for errors, and compare another insurer because companies can use permitted rating information differently.
What Actually Changes an Auto Insurance Price?
Insurance pricing can reflect many permitted factors, including location, driving record, vehicle, coverage selected, deductibles, prior insurance, claims history, mileage or vehicle use, discounts, and other insurer-specific rating information.
Before buying a car or changing coverage, the car insurance cost factors can help you organize the vehicle, deductible, prior-insurance, and coverage choices that should stay consistent when you request real quotes.
| Cost Factor | Why It Can Matter | What to Do |
|---|---|---|
| Vehicle | Repair cost, value, safety, theft experience, and use can affect pricing. | Check insurance costs before purchasing the vehicle. |
| Driving record | Accidents, tickets, and serious violations can change the insurer’s risk assessment. | Use accurate driving information on every quote. |
| Coverage limits | More liability or physical-damage protection generally changes the premium. | Compare equivalent limits across companies. |
| Deductible | A higher deductible can reduce some physical-damage premiums. | Choose only an amount you could realistically pay after a loss. |
| Prior insurance | Previous coverage is one of the factors identified by the NAIC. | Keep prior-coverage dates accurate and avoid unnecessary lapses. |
| Discounts | Eligibility varies by insurer and state. | Ask which discounts are included and which still need verification. |
Ways to Lower Cost Without Cutting the Wrong Protection
Triple-I recommends shopping around and getting at least three price quotes. It also recommends checking insurance costs before buying a vehicle, considering higher deductibles that you could afford, evaluating collision or comprehensive on older vehicles, and asking about discounts.
Changes worth comparing
- Equivalent quotes from several insurers
- Different physical-damage deductibles
- Available multi-policy or multi-vehicle discounts
- Low-mileage or other verified discounts where offered
- Collision or comprehensive on an older paid-off vehicle
Changes that need more caution
- Reducing liability limits
- Removing coverage required by a lender or lease
- Choosing a deductible you could not pay after a claim
- Canceling before replacement coverage is active
- Ignoring fees or the total policy premium
Higher Deductibles Can Lower Premiums but Increase Claim-Time Risk
A higher collision or comprehensive deductible can reduce the premium, but the savings only help if the deductible is still affordable when a claim happens. For a household with little emergency savings, moving from a manageable deductible to a much larger one can simply shift the financial problem from the monthly bill to the day of the loss.
Compare the annual premium difference against the extra amount you would need to pay after a covered claim. If the vehicle is financed or leased, also check the loan or lease agreement before changing physical-damage coverage.
Older Paid-Off Vehicles Need a Different Calculation
Collision and comprehensive can become less cost-effective as a vehicle loses value, particularly when the car is paid off. Triple-I recommends evaluating whether those coverages still make sense on an older vehicle rather than automatically renewing the same structure every year.
Dropping physical-damage coverage means accepting the risk of paying for your own vehicle repair or replacement after certain losses. Compare the vehicle’s value, annual coverage cost, deductible, and your ability to replace the car before making that decision.
Avoid a Coverage Lapse While Looking for a Cheaper Policy
Cutting cost should not create a period with no insurance. If you find a cheaper replacement, confirm that the new policy has been issued, verify its effective date and time, and save proof of insurance before the old policy’s cancellation takes effect.
When replacing an existing policy, confirm that the new coverage has been issued, verify its effective date and time, save proof of insurance, and only then cancel the old policy for the appropriate date.
If a payment is becoming difficult: contact the current insurer before assuming there is a grace period or simply allowing the policy to cancel. Ask about the amount due, cancellation date, available payment methods, and whether a lower-cost policy structure is available before coverage ends.
What If Every Quote Still Feels Too Expensive?
First make sure you are comparing equivalent policies. A quote can look cheaper or more expensive because the liability limits, deductibles, drivers, vehicles, optional benefits, policy term, or payment plan are different.
Steps worth trying
- Get quotes from several insurers rather than relying on one company.
- Ask for both the legal minimum and a higher-limit option so you can see the price difference.
- Check whether the vehicle itself is a major cost driver.
- Ask which discounts have actually been applied.
- Check the state insurance department for official assistance, assigned-risk, or residual-market resources where available.
- Review whether a different deductible is affordable rather than simply choosing the highest one.
- Compare the total premium and fees, not just the monthly installment.
Where Fred Loya Fits Into an Affordability Comparison
Fred Loya can be one company to compare in states where it operates, particularly for drivers who value local-office access or want an auto-focused insurer. It should still be compared on the same basis as every other company: equivalent liability limits, deductibles, optional coverage, total premium, fees, and policy terms.
Do not assume that “no credit check,” a local office, or a lower first payment automatically makes a policy the least expensive overall. The issued policy and total premium matter more than the marketing label.
If another insurer offers a policy that fits your budget better, the timing for switching car insurance without a coverage gap matters just as much as the price difference. Confirm the replacement coverage before ending the current policy.
Frequently Asked Questions About Low Income Car Insurance
Is there a nationwide low-income auto insurance program?
No single nationwide program exists. Assistance options depend on the state. Check the official state insurance department or assigned-risk plan for current programs and eligibility.
Does California have a low-cost auto insurance program?
Yes. California operates the California Low Cost Automobile Insurance Program for qualifying drivers. Current eligibility and rates should be checked directly with the program or California Department of Insurance.
Does the California program use the normal 30/60/15 liability limits?
No. California says CLCA uses lower 10/20/3 liability limits that remain legally valid within that special program, even though the state’s standard private-passenger minimum limits increased in 2025.
Will a higher deductible always save enough money to be worthwhile?
No. A higher deductible can lower some premiums, but the savings should be compared with the extra amount you would have to pay after a covered loss.
Can credit affect car insurance?
In states where the practice is allowed, insurers may use credit-based insurance scores as one rating or underwriting factor. State restrictions vary, and these scores are different from traditional lending credit scores.
Compare Auto Insurance Quotes by ZIP Code
Enter your ZIP code to compare auto insurance quote options. Match equivalent coverage limits and deductibles, then compare the total premium and policy terms.
Compare the actual policy, not only the monthly payment.
Sources
This article uses current state and national consumer-insurance resources. Program eligibility, premiums, state requirements, credit-score restrictions, and policy terms can change, so time-sensitive information should be checked directly with the relevant regulator, program, or insurer.
- California Department of Insurance — California Low Cost Automobile Insurance Program
- California Department of Insurance — Auto Insurance and CLCA Eligibility Information
- California Department of Insurance — 2025 Liability Limit Changes and CLCA Limits
- National Association of Insurance Commissioners — Credit-Based Insurance Scores
- National Association of Insurance Commissioners — Auto Insurance
- Fred Loya Insurance — Official Website and No-Credit-Check Information
- Triple-I — Nine Ways to Lower Your Auto Insurance Costs