Category: quotes

  • Fred Loya Insurance Payment: How to Pay and What to Check

    Article Information

    By LoyalInsurance.org Editorial Team

    Independent guide for U.S. drivers researching Fred Loya Insurance payment options, online account tools, payment timing, and policy document access.

    • Fred Loya Insurance
    • Insurance Payments
    • Policy Management
    Editorial disclosure

    This guide summarizes publicly available Fred Loya Insurance information. Payment terms, fees, cancellation rules, and policy status can vary by policy and state, so confirm time-sensitive details on Fred Loya’s current payment system or in your policy documents. LoyalInsurance.org is an independent informational website and is not affiliated with Fred Loya Insurance.

    Official payment access

    If you are ready to pay an existing policy, you can use Fred Loya’s official online payment form and verify the policy information, amount, and payment details before submitting.

    Fred Loya also provides online account tools for payments, insurance ID cards, declaration pages, policy details, and payment summaries. This guide explains what to check before paying, how to document the transaction, and what to do when a payment is late or the policy status is unclear.

    Payment deadline: Fred Loya’s current payment page states that payments are due by 12:00 AM MST on the due date, while its FAQ uses 12:00 a.m. MDT. Because the company’s public pages use different Mountain Time abbreviations, avoid relying on the abbreviation alone and pay before the due-date cutoff whenever possible.
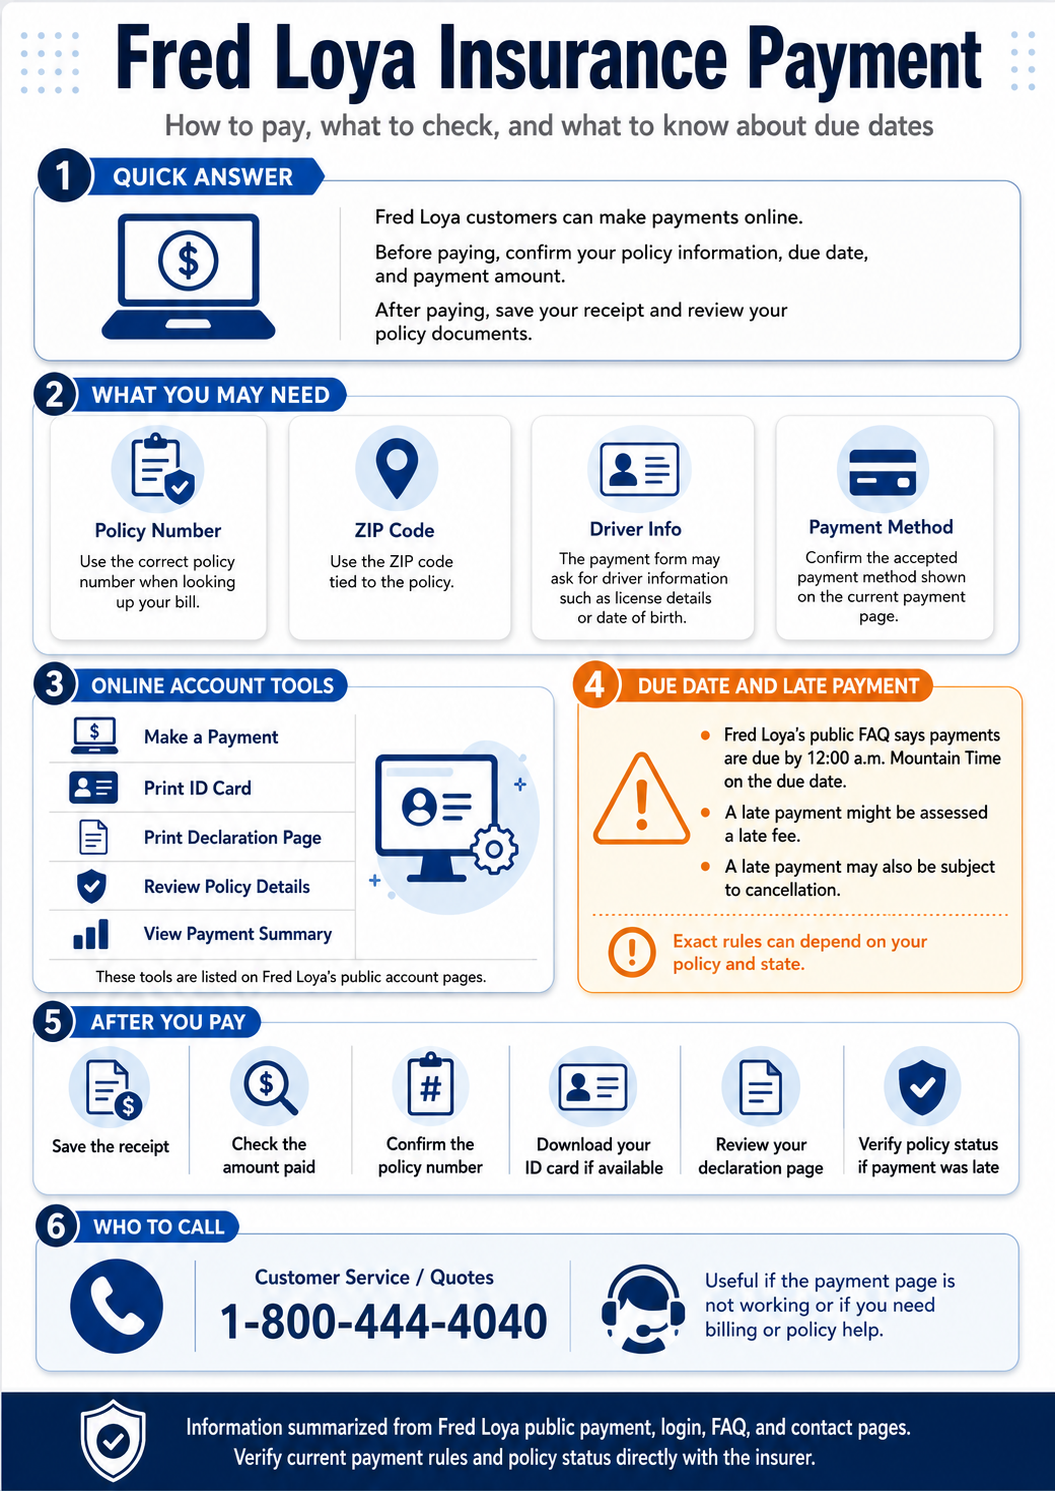
    Infographic explaining Fred Loya Insurance payment steps, online account tools, due dates, late payment reminders, receipts, and customer service phone number.
    A quick guide to Fred Loya Insurance payments, what to check before paying, and what to do after submitting a payment.

    How Fred Loya Insurance Payments Work

    Fred Loya Insurance provides online payment access for customers paying an existing auto insurance policy. The company’s current payment page uses a three-stage process: bill information, payment information, and review information.

    The first stage helps identify the policy before card information is entered. The review stage gives the policyholder another opportunity to check the payment information before submitting the transaction.

    That matters because an insurance payment is more than a checkout transaction. Drivers should make sure the payment is associated with the intended policy and keep evidence of the transaction, especially when paying near the due date.

    What You May Need Before Making a Payment

    Fred Loya’s current public payment page displays fields for information including policy number, ZIP code, driver license number, and date of birth. The fields shown can change, so use the information on your policy documents or billing notice and follow the current payment screen.

    Policy Number

    The policy number connects the payment to the insurance policy. Check it carefully against your policy documents or billing notice.

    ZIP Code

    The payment system may use the ZIP code to locate or verify the policy. Use the ZIP code associated with the policy unless the current form says otherwise.

    Driver Information

    Driver license information or date of birth may be requested to identify the policy. Enter the information exactly as requested on the payment screen.

    Payment Method

    The current payment page displays credit-card fields. Review the amount and any terms shown before submitting the transaction.

    Online Payment, Login, and Policy Tools

    Fred Loya’s public login page says customers can manage several policy functions online. The listed tools include making a payment, printing an insurance ID card, printing a declaration page, reviewing policy details, and viewing a payment summary.

    Online Tool What It Can Help With What to Check
    Make a Payment Pay an existing Fred Loya policy through the online payment system. Check the policy, amount, and payment information before submitting.
    Print ID Card Access available proof-of-insurance documents. Check the insured information, vehicle, and effective dates.
    Print Declaration Page Access a document summarizing important policy information. Review vehicles, drivers, coverage, limits, and other policy details.
    Review Policy Details Look over policy information through the customer account. Verify names, addresses, vehicles, coverage, and billing information.
    Payment Summary Review payment information available through the account. Keep useful records when paying close to the due date or resolving a billing issue.

    Step-by-Step: Making a Fred Loya Payment

    Gather the policy information

    Have the policy number, ZIP code, relevant driver information, billing notice, and payment method available before beginning.

    Check the due date before paying

    Fred Loya’s public pages place the payment deadline at midnight Mountain Time on the due date, although the official pages currently use both MST and MDT abbreviations. Paying earlier reduces the risk of a time-zone or processing dispute.

    Review the transaction before submitting

    Check the policy information, payment amount, card information, and any terms displayed on the current payment screen before clicking the final payment button.

    Save the payment confirmation

    Fred Loya’s payment page says a receipt is sent to the email address on file after payment and shows options to download a payment receipt, insurance ID card, and declaration page. Save the records that are available to you.

    Late Payments, Grace Periods, and Cancellation Risk

    Fred Loya’s public FAQ says there is no general grace period in the answer it provides: payment is due on the due date, and a late payment might result in a late fee or make the policy subject to cancellation.

    That does not establish the exact outcome for every policy. Cancellation timing, notices, reinstatement options, and policy status can depend on state rules, policy documents, billing history, and the specific notice sent to the policyholder.

    If the policy is already late: check any billing or cancellation notice, keep proof of your payment attempt, and contact Fred Loya directly rather than assuming that submitting a payment automatically restores or confirms coverage.

    A late-payment issue can become more important when an accident occurs around the same time, because payment history and policy status are separate from the handling of a loss. In that situation, the way the Fred Loya insurance claim process moves forward can involve issues that are separate from the payment or billing problem.

    Situation What to Do
    The due date has already passed Check the billing notice and current policy status before assuming coverage remains active.
    The online form still accepts payment Save the confirmation, but verify policy status if a late-payment or cancellation issue already exists.
    You received a cancellation notice Review the notice and contact Fred Loya directly about the status and available options.
    A late fee appears Review the amount shown and ask customer service for clarification if it does not match your records.

    What to Check After Paying

    After submitting a payment, confirm that the transaction has produced a usable record. This is especially important when the payment was made close to the deadline or after receiving a billing warning.

    • Save the receipt. Keep the payment confirmation, email receipt, PDF, or screenshot available for your records.
    • Check the policy number. Make sure the confirmation is associated with the policy you intended to pay.
    • Review the amount. Confirm the amount paid and the payment information shown on the transaction record.
    • Download available documents. Save the ID card or declaration page if the system makes them available.
    • Verify policy status when necessary. If the account was already late or subject to cancellation, confirm the current status directly.

    When to Pay Online and When to Call

    Online payment is practical when the policy can be located, the amount appears correct, and no unresolved cancellation or billing issue is involved. Calling customer service may be more appropriate when the account is late, the payment form fails, the amount appears incorrect, or a cancellation notice is involved.

    Online Payment May Make Sense When

    The policy information matches, the amount is expected, and the payment system is functioning normally.

    Calling May Make Sense When

    The policy is already late, the website reports an error, the billing notice is unclear, or you need confirmation of current policy status.

    Fred Loya currently lists 1-800-444-4040 for quotes and customer service. For billing, claims, roadside assistance, or local-office questions, the Loya insurance phone numbers and department contacts can help you identify where to call.

    Common Payment Mistakes to Avoid

    Waiting Until the Deadline

    Paying earlier gives you time to deal with a website error, incorrect policy information, or a payment that does not immediately confirm.

    Entering Mismatched Policy Information

    A wrong policy number, ZIP code, or driver detail may prevent the system from locating the correct policy.

    Closing the Page Without Saving Proof

    Keep the receipt or confirmation so you have a record if a billing or policy-status question occurs later.

    Assuming Payment Automatically Confirms Coverage

    When a policy is already late or cancellation has occurred, submitting a payment does not by itself answer every coverage or reinstatement question.

    Use Payment Time to Review the Policy

    Paying the bill keeps attention on the current policy, but it is also a useful time to review whether the listed drivers, vehicles, address, deductibles, and coverage still match your situation.

    If you are approaching renewal or reconsidering the policy, the question of how much auto insurance coverage you may need becomes especially relevant when comparing liability limits, physical-damage coverage, deductibles, and other policy choices instead of focusing only on the monthly payment.

    Useful habit: periodically compare the policy documents with your current vehicle, address, listed drivers, and coverage needs so outdated information can be addressed.

    Frequently Asked Questions

    Can I pay Fred Loya Insurance online?

    Yes. Fred Loya’s official FAQ says customers can make payments online through its secure payment form.

    What information may be needed for an online payment?

    The current payment page displays fields including policy number, ZIP code, driver license number, and date of birth. Follow the fields shown by the live payment system because they can change.

    When is a Fred Loya payment due?

    Fred Loya’s public pages state that payment is due by midnight Mountain Time on the due date. The current payment page uses MST while the FAQ uses MDT, so paying before the cutoff is safer than relying on the abbreviation.

    Does Fred Loya provide a general grace period?

    Its public FAQ says no general grace period applies in the answer provided there and warns that a late payment might result in a late fee or make the policy subject to cancellation.

    What should I do if the payment website does not work?

    Fred Loya currently lists 1-800-444-4040 for customer service. If the payment is time-sensitive, keep evidence of the failed payment attempt and contact the insurer directly.

    Bottom Line

    Fred Loya provides online payment and policy-management tools, but the transaction should be handled carefully when a due date or cancellation issue is involved.

    Before paying, check the policy information and amount. After paying, keep the receipt and available policy documents. If the payment is already late or the policy status is unclear, confirm the status directly rather than assuming that payment alone resolves the issue.

    Sources and Editorial Note

    [1] Fred Loya Insurance’s official online payment page was reviewed for the payment workflow, identification fields, deadline wording, receipt information, and downloadable policy documents.

    [2] The Fred Loya customer login page was reviewed for the online tools available for payments, ID cards, declaration pages, policy details, and payment summaries.

    [3] Fred Loya’s official insurance FAQ was reviewed for online-payment availability, due-date guidance, grace-period language, and possible consequences of late payment.

    [4] The Fred Loya contact page was reviewed for current customer-service and claims contact information.

    Editorial note: LoyalInsurance.org independently summarizes publicly available insurance information to help readers understand common policy and payment questions. Because insurer systems and policy terms can change, confirm urgent billing or coverage questions with the insurer or your current policy documents.

    Optional: Compare Other Coverage

    Compare Auto Insurance Quotes by ZIP Code

    If you are reviewing alternatives before renewal, enter your ZIP code to compare quote options and evaluate price, coverage limits, deductibles, and policy terms.

    Quote comparison is separate from making or resolving a Fred Loya policy payment.
  • Cheap Car Insurance In LA

    LoyalInsurance.org Editorial Team Created: June 16, 2026 Updated: September 12, 2026
    Topic: Cheap car insurance in Los Angeles Focus: California requirements, affordability, CLCA, rate factors, and quote comparison
    Los Angeles Car Insurance

    Finding cheap car insurance in LA is less about chasing one advertised price and more about comparing the same coverage across several insurers. California regulates how auto insurance is priced, and the amount you pay can still vary significantly from one company to another based on your driving record, annual mileage, years of driving experience, garaging area, vehicle, coverage choices, and other approved rating factors.

    Los Angeles drivers should start with California’s current liability requirements, decide how much protection they can realistically afford to keep in force, and then compare quotes using the same drivers, vehicle, limits, deductibles, and policy term.

    California minimum

    $30,000 / $60,000 bodily injury and $15,000 property damage for a standard auto policy.

    Good Driver rule

    Qualifying California Good Drivers must receive a rate at least 20% lower than the same insurer’s non-Good-Driver rate.

    Low-income option

    California operates CLCA for qualifying income-eligible good or new drivers.

    Best comparison method

    Use equivalent limits and deductibles, then compare the total premium rather than only the monthly installment.

    Why Auto Insurance Prices Vary Across Los Angeles

    California gives the greatest rating weight to three primary factors: the driver’s safety record, annual miles driven, and years of driving experience. Insurers can also use approved secondary factors. The California Department of Insurance notes that claim frequency and severity in the area where you live can also affect pricing, which helps explain why otherwise similar drivers can receive different premiums.

    That does not mean one Los Angeles ZIP code is always cheap or expensive. The same neighborhood can produce very different quotes depending on the insurer, vehicle, driving history, mileage, coverage, and deductible.

    Driving safety record

    Tickets and at-fault accidents are among California’s primary auto-rating considerations.

    Annual mileage

    How much you drive is another primary California rating factor.

    Years of driving experience

    Driving experience is the third primary factor identified in California’s rating framework.

    Garaging area and vehicle

    Approved secondary factors can include territory and vehicle-related characteristics.

    California Minimum Auto Insurance Requirements

    Los Angeles follows California’s statewide financial-responsibility rules. For standard private-passenger auto policies, the minimum liability limits are now $30,000 for injury or death to one person, $60,000 for injury or death to more than one person in one accident, and $15,000 for property damage.

    Liability Coverage California Standard Minimum
    Bodily injury or death — one person $30,000
    Bodily injury or death — more than one person $60,000 per accident
    Property damage $15,000 per accident

    The legal minimum is only a baseline. If a covered loss exceeds the liability limit, the remaining amount can become your responsibility. The broader decision around how much auto insurance coverage fits your situation should consider your assets, vehicle, lender requirements, deductible tolerance, and the loss you could absorb yourself.

    Vehicle coverage is separate: liability coverage is primarily for covered injury or property damage to others. Collision and comprehensive are separate coverages used to protect your own vehicle when they apply.

    Use California’s 2026 Premium Comparison Tool

    The California Department of Insurance publishes a 2026 Automobile Insurance Comparison Tool using hypothetical driver and vehicle profiles. It can help Los Angeles shoppers see how sample premiums differ between participating insurers before requesting personalized quotes.

    The Department specifically warns that the survey results are not quotes. They are sample premiums built from hypothetical profiles, and the amount an insurer actually charges you can differ because of your individual information, discounts, surcharges, coverage choices, and approved rating plan.

    Useful comparison: California Department of Insurance premium comparison tools can provide a neutral starting point before you request insurer-specific quotes.

    California Good Driver Discounts

    California’s Good Driver provision can be especially important when affordability is the goal. The Department of Insurance says every auto insurer must offer coverage for Good Drivers and that a qualifying Good Driver’s rate must be at least 20% lower than the same insurer’s non-Good-Driver rate would be.

    California’s Good Driver rules generally require at least three consecutive years of licensing, no more than one DMV point during the relevant period, and no principally-at-fault accident that resulted in bodily injury or death, subject to the full statutory eligibility rules. Ask the insurer whether the quote reflects Good Driver status when you qualify.

    Other Discounts: Ask, but Do Not Assume

    Insurers may offer additional approved credits or discounts, but availability and eligibility vary. Instead of relying on generic percentage ranges, ask each insurer which discounts are available to your profile and whether they are already reflected in the quoted premium.

    • Multi-policy or multi-vehicle discounts where offered
    • Low-mileage or usage-related discounts where approved and available
    • Good student or driver-training discounts when eligibility rules are met
    • Vehicle-related or anti-theft discounts where offered
    • Other insurer-specific credits shown in the approved rate plan

    California Low Cost Auto Insurance for Eligible Drivers

    California’s Low Cost Automobile Insurance Program (CLCA) is a state-sponsored option for income-eligible good or new drivers who need affordable liability insurance. It is not a nationwide program and it is not the same as buying a standard minimum-limit policy.

    Current California guidance says CLCA applicants generally must have annual household income at or below 250% of the federal poverty level, a valid California driver’s license, a vehicle valued at $25,000 or less, be at least 16 years old, and meet the program’s good-driver requirements or qualify as a new driver. Applicants under 18 must be legally emancipated, and AB 60 licenses are accepted.

    Drivers who want more detail on affordability programs can compare low-income car insurance and state assistance options before deciding whether CLCA or a standard-market policy makes more sense.

    CLCA Liability Limits

    • $10,000 bodily injury or death per person
    • $20,000 bodily injury or death per accident
    • $3,000 property damage per accident

    These limits are lower than California’s standard 30/60/15 minimums, but California specifically recognizes them within the CLCA program.

    What If Standard Auto Insurance Is Hard to Obtain?

    Drivers with multiple accidents, tickets, or other underwriting issues may have trouble finding coverage in the voluntary market. California maintains the California Automobile Assigned Risk Plan (CAARP) for motorists who cannot obtain standard-market liability insurance.

    The California Department of Insurance explains that CAARP assigns eligible drivers to participating insurers. The program is different from CLCA: CLCA is aimed at income-eligible good or new drivers, while CAARP addresses access to coverage for drivers who cannot obtain insurance in the regular market.

    CAARP information: California currently directs consumers to CAARP at 1-800-622-0954 for more information.

    How to Compare Cheap Car Insurance Quotes in LA

    Compare the same coverage structure across companies. A quote with lower liability limits, no collision or comprehensive, or a much higher deductible can look cheaper without being equivalent.

    1. Match drivers and vehicles

    Use the same household drivers, vehicle information, garaging address, and annual mileage.

    2. Match liability limits

    Do not compare a 30/60/15 quote against a quote with substantially higher liability protection.

    3. Match deductibles

    Compare collision and comprehensive with the same deductible whenever possible.

    4. Check optional coverage

    Rental, roadside, medical coverage, UM/UIM, and other benefits can change the premium.

    5. Compare total premium

    Down payments and monthly installments do not show the complete policy cost.

    6. Confirm the effective date

    A cheaper quote is not useful if replacing the old policy creates a coverage gap.

    ZIP Code and Neighborhood: What You Can Say Reliably

    Where the vehicle is garaged can affect a California auto premium because insurers may use approved territory-related rating information. But there is no reliable universal rule that one Los Angeles ZIP code is always cheaper than another for every driver and insurer.

    Avoid neighborhood “cheap vs. expensive” rankings unless they come from a current, documented rate dataset using the same driver, vehicle, and coverage assumptions. For your own policy, use the actual garaging address and request personalized quotes.

    How to Verify an Insurance Company, Agent, or Broker in California

    Instead of relying on an unsourced list of “best local agents,” use California’s regulatory tools. The Department of Insurance lets consumers check insurance-company information, complaint studies, enforcement actions, and agent or broker license status.

    Check an agent or broker

    Verify the person’s or business entity’s California license status and discipline history before buying.

    Check an insurer

    Use California company profiles and complaint information to confirm licensing and consumer-service records.

    California requires licensed insurance agents and brokers to display their license number on business cards and insurance marketing materials they provide to consumers. If someone cannot provide a license number, verify the person or business through the California Department of Insurance before paying money or submitting sensitive information.

    Older Vehicles and Higher Deductibles

    An older paid-off vehicle may not need the same physical-damage coverage as a newer financed vehicle. Compare the annual cost of collision and comprehensive with the vehicle’s current value, the deductible, and your ability to repair or replace the car yourself.

    A higher deductible can lower some physical-damage premiums, but only choose an amount you could realistically pay after a covered loss. If the car is financed or leased, check the lender or lease agreement before changing coverage.

    Avoid a Coverage Gap When Replacing a Policy

    If another insurer offers a lower price, do not cancel the existing policy based only on a quote. Confirm the replacement policy is issued, verify the effective date and time, and save proof of insurance first.

    A lapse can create legal, registration, lender, and future-pricing problems, so confirm replacement coverage before ending the current policy.

    What to Watch for in a Very Cheap Quote

    If Fred Loya is one of the companies in your Los Angeles comparison, review the Loya car insurance coverage and policy options alongside competing quotes so you can compare the same liability limits, deductibles, physical-damage coverage, payment terms, and service access.

    Lower liability limits

    A cheaper quote may simply provide less protection if the limits are lower.

    Higher deductibles

    A lower premium can shift more of the claim cost to you.

    Different policy term

    Compare premiums over the same term before deciding one quote is cheaper.

    Missing optional coverage

    Check whether rental, roadside, medical, UM/UIM, or physical-damage coverage was removed.

    Frequently Asked Questions About Cheap Car Insurance in LA

    What is the cheapest car insurance company in Los Angeles?

    There is no single cheapest insurer for every Los Angeles driver. California’s premium comparison tool can show sample differences between insurers, but your own quote depends on your driving record, mileage, experience, vehicle, garaging area, coverage, and other approved factors.

    How much is car insurance per month in Los Angeles?

    There is no reliable single monthly price for all LA drivers. Use the California Department of Insurance comparison tool for sample premiums, then request personalized quotes with the same coverage limits and deductibles.

    Can a driver with an AB 60 license qualify for California’s Low Cost Auto Insurance Program?

    Yes. Current CLCA materials state that an AB 60 California driver’s license is accepted, subject to the program’s other income, vehicle, age, and driving-record eligibility rules.

    Is California’s Low Cost Auto Insurance Program the same as standard minimum coverage?

    No. CLCA is a special state program with its own eligibility requirements and 10/20/3 liability limits. Standard California private-passenger minimum liability limits are 30/60/15.

    What if no standard insurer will cover me?

    California’s Assigned Risk Plan can provide a path to liability insurance for motorists who cannot obtain coverage in the voluntary market.

    What if I already have insurance and find a cheaper quote?

    Confirm the replacement policy first. The steps for switching car insurance without a coverage gap help you line up the new effective date before canceling the current policy.

    Cheap Car Insurance in LA: Final Checklist

    • Start with California’s current 30/60/15 standard liability minimums.
    • Check whether you qualify for the California Good Driver discount.
    • Compare several insurers using identical coverage and deductibles.
    • Use California’s 2026 premium comparison tool as a sample-rate reference, not as a quote.
    • Check CLCA if household income and other eligibility rules fit your situation.
    • Check CAARP if you cannot obtain coverage in the standard market.
    • Verify the insurer, agent, or broker through California’s licensing tools.
    • Confirm replacement coverage before canceling an existing policy.

    Compare Los Angeles Auto Insurance Quotes

    Enter your ZIP code to compare auto insurance quote options. Use the same drivers, vehicle, liability limits, deductibles, and major coverage choices when comparing results.

    Compare equivalent coverage, deductibles, total premium, and policy terms before choosing a policy.

    Sources

    1. California Department of Insurance — Automobile Insurance
    2. California Department of Insurance — 2025 Liability Limit Changes and CLCA Limits
    3. California Department of Insurance — 2026 Automobile Premium Comparison
    4. California Department of Insurance — Auto Rating Factors and Shopping Information
    5. California Low Cost Auto Insurance Program — Qualifications
    6. California Department of Insurance — California Low Cost Automobile Insurance Program
    7. California Department of Insurance — Company and Agent/Broker Information
    8. California Department of Insurance — Check an Agent or Broker License
    9. California Department of Insurance — Finding and Verifying an Agent or Broker
    10. California Automobile Assigned Risk Plan — Official CAARP Information
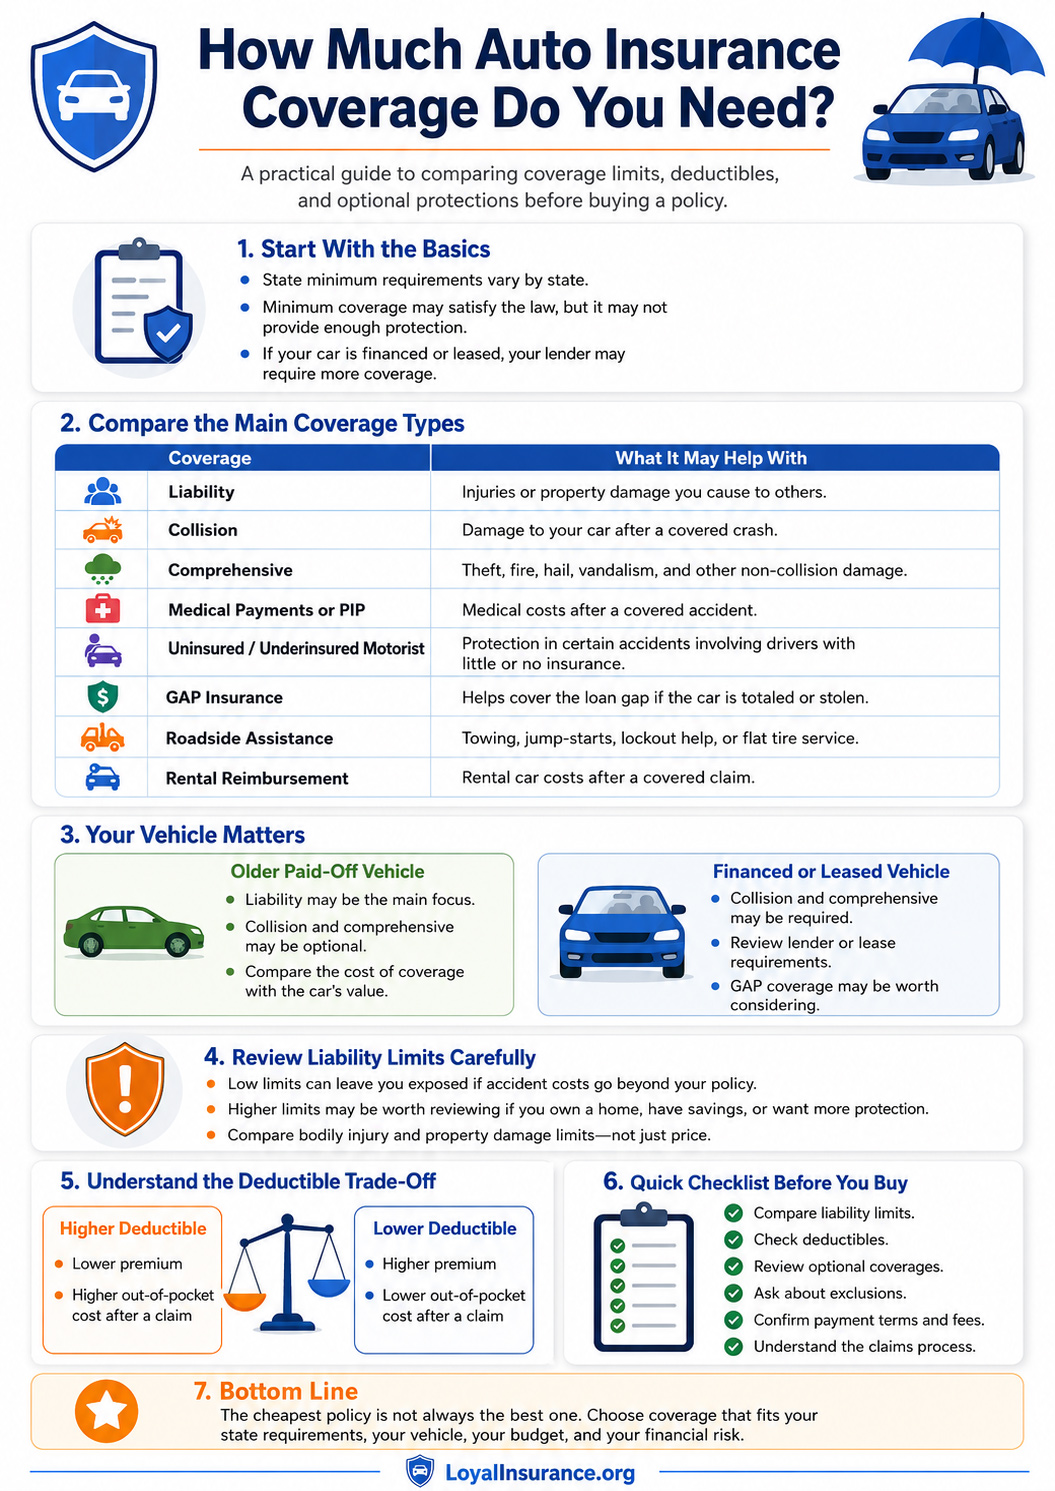
  • How Much Auto Insurance Coverage Do You Need?

    Auto Insurance Coverage

    There is no single amount of auto insurance coverage that is right for every driver. The appropriate policy depends on state requirements, the value and financing of the vehicle, your liability exposure, the amount you could pay after a loss, and the risks you want the policy to absorb.

    A useful starting point is to separate three questions: how much liability protection you want, whether you need coverage for your own vehicle, and which optional benefits are worth paying for. State-required minimums are legal baselines, not personalized recommendations.

    Start with State requirements
    Liability Match your financial exposure
    Your vehicle Check collision & comprehensive
    Deductible Choose an amount you can pay
    Auto insurance coverage decision factors including liability limits, deductibles, collision, comprehensive, GAP, lender requirements, and optional coverage.

    Start With the State Minimum, but Treat It as a Floor

    State law determines the minimum auto insurance or financial-responsibility requirements that apply where the vehicle is insured. Those requirements can include liability coverage and, depending on the state, other protections such as PIP or uninsured-motorist coverage.

    Minimum limits can make a policy less expensive, but they also cap how much the policy can pay for a covered liability loss. If you are considering the lowest legal option, the tradeoffs behind basic auto liability coverage are worth checking before you decide that the minimum is enough for your situation.

    Legal minimum vs. financial protection: a policy can satisfy state law and still leave you personally responsible for amounts above the policy limits.

    How to Think About Liability Limits

    Liability coverage generally addresses covered bodily injury or property damage for which you are legally responsible. The limit is the maximum the policy will pay under the applicable coverage, subject to the policy terms.

    Instead of choosing a liability limit by habit, consider the financial consequences of a serious accident. Assets, savings, income, driving exposure, and the amount of loss you could absorb yourself can all affect whether a higher liability limit is worth comparing.

    Higher liability limits may deserve closer consideration when

    • You have savings, investments, home equity, or other assets you want to protect.
    • You have meaningful income or future earning power.
    • You drive frequently or in dense traffic.
    • You regularly carry passengers.
    • You want more protection than the legal minimum.
    • An umbrella policy or other insurer requirement calls for specific underlying auto limits.

    Coverage for Your Own Vehicle Is a Separate Decision

    Liability coverage does not generally pay to repair your own vehicle after an at-fault collision. Collision and comprehensive are the main physical-damage coverages used to protect the insured vehicle, subject to deductibles, exclusions, and policy terms.

    Collision generally addresses covered damage from a collision, while comprehensive generally addresses certain covered non-collision losses such as theft, fire, hail, flood, vandalism, or animal impact. If you have an auto loan, the NAIC notes that the lender typically requires collision and comprehensive coverage.

    Older paid-off vehicle

    • Compare the annual physical-damage premium with the vehicle’s current value.
    • Consider whether you could repair or replace the vehicle yourself.
    • Check the deductible before deciding the coverage is worth keeping.
    • Remember that dropping coverage transfers more loss risk to you.

    Financed or leased vehicle

    • Check the finance or lease agreement before changing coverage.
    • Collision and comprehensive may be contractually required.
    • Check whether the lender or lease agreement sets deductible requirements.
    • Keep the lienholder information correct on the policy.

    Uninsured Motorist, PIP, and Medical Payments

    These coverages solve different problems and their availability or requirements vary by state. Uninsured or underinsured motorist coverage can apply when an at-fault driver has no insurance or insufficient insurance, while PIP or Medical Payments can address specified injury-related expenses depending on the policy and state law.

    Check whether each coverage is required, automatically included, optional, or rejectable in writing where you live. Also compare the limits rather than assuming the coverage name alone tells you how much protection you have.

    Choose a Deductible You Could Actually Pay

    The deductible is the amount you are responsible for under certain coverages before the insurer pays the remainder of a covered loss, subject to the policy terms. Higher deductibles can reduce some physical-damage premiums, but they also increase your out-of-pocket obligation after a claim.

    When comparing deductible scenarios, the car insurance cost factors can help you organize how the vehicle, coverage level, prior insurance, and deductible choices change the comparison before you request live quotes.

    Choice Possible Benefit Tradeoff
    Higher deductible Can reduce some collision or comprehensive premiums. You must absorb more of a covered loss yourself.
    Lower deductible Reduces the amount you may need to pay after an applicable covered loss. The premium can be higher.
    No physical-damage coverage Can substantially reduce premium on some paid-off vehicles. You may receive no policy payment for damage to your own car after certain losses.

    GAP Is Different From Ordinary Auto Insurance Coverage

    GAP is generally an optional product intended to address the difference between what you still owe on an auto loan and what the primary auto insurer pays when the vehicle is stolen or totaled and the loan balance is higher than the vehicle value. The Consumer Financial Protection Bureau notes that GAP can be offered by dealers, lenders, or insurers and that prices can vary significantly.

    GAP should not be confused with collision or comprehensive coverage. It is tied to the financing shortfall, and eligibility restrictions or exclusions can apply. Compare the cost and terms before adding it to the loan or policy.

    GAP check: If a dealer or lender says GAP is required, ask where that requirement appears in the contract. CFPB says GAP is generally optional in most auto-loan situations.

    Roadside Assistance and Rental Reimbursement Are Convenience Coverages

    Roadside assistance and rental reimbursement can be useful, but they serve different purposes from liability or physical-damage coverage. Roadside benefits can cover specified services after a breakdown or roadside event, while rental reimbursement can help with temporary transportation when the policy conditions are met.

    Compare benefit limits, exclusions, qualifying events, and cost. If you already receive roadside service through a vehicle warranty, credit card, auto club, or another source, check for unnecessary duplication.

    A Practical Framework for Deciding How Much Coverage to Buy

    Question Why It Matters What to Review
    What does my state require? Establishes the legal floor. Liability, PIP, UM/UIM, or other state-specific requirements.
    How much liability risk can I absorb? Damages above the limit can become your responsibility. Assets, income, savings, driving exposure, and available higher limits.
    Could I replace my car myself? Helps determine how valuable physical-damage coverage may be. Vehicle value, collision/comprehensive premium, and deductible.
    Does a lender require coverage? Finance and lease contracts can require more than state law. Collision, comprehensive, deductible limits, and lienholder requirements.
    Could I afford the deductible tomorrow? A lower premium does not help if the deductible is unusable after a loss. Emergency savings and the deductible on each coverage.
    Which optional benefits would I actually use? Prevents paying for benefits that do not fit your situation. Rental, roadside, GAP, medical coverage, and other optional benefits.

    Balance Coverage With Affordability

    More coverage is not automatically better if the premium becomes impossible to maintain. A policy that repeatedly risks cancellation can create a different kind of financial problem. Compare several insurers using the same limits and deductibles, then decide which level of protection you can realistically keep in force.

    If affordability is forcing you toward the minimum, compare the price difference between the legal floor and the next higher liability option. Sometimes the increase is manageable; sometimes it is not. The decision should be based on real quotes rather than assumptions.

    Revisit Coverage When Your Situation Changes

    Coverage that made sense several years ago may not fit after buying a different vehicle, paying off a loan, moving, adding a driver, changing commute patterns, accumulating savings, or changing household finances. Renewal is a useful time to check those changes rather than automatically repeating the prior limits.

    If a better policy will replace your current one, the timing for switching car insurance without a coverage gap matters just as much as the new limits. Confirm the replacement policy and effective date before ending the old coverage.

    Before buying or renewing, confirm

    • The legal insurer name
    • Policy effective and expiration dates
    • Bodily-injury and property-damage liability limits
    • Collision and comprehensive coverage and deductibles, if included
    • UM/UIM, PIP, MedPay, or other state-specific coverage
    • Rental, roadside, GAP, or other optional benefits
    • Listed and excluded drivers
    • Total premium, payment schedule, and applicable fees
    • Claim-reporting information

    Frequently Asked Questions About Auto Insurance Coverage

    Is state-minimum insurance enough?

    It can satisfy the legal requirement, but it may not provide enough financial protection for every driver. Compare the potential loss above the minimum limits with the cost of higher limits.

    How much liability coverage should I carry?

    There is no universal number. Start with the state requirement, then consider your assets, income, savings, driving exposure, available higher limits, and the amount of financial risk you are willing to retain.

    Do I need collision and comprehensive?

    A lender commonly requires them on a financed vehicle. On a paid-off vehicle, compare the premium and deductible with the vehicle’s value and your ability to repair or replace it yourself.

    Is GAP insurance required?

    GAP is generally optional in most auto-loan situations. It can be useful when the loan balance is higher than the vehicle’s value, but check the contract, price, eligibility restrictions, and cancellation terms before buying.

    Should I choose a higher deductible to lower the premium?

    Only if the savings are worthwhile and you could realistically pay the larger deductible after a covered loss.

    Compare Coverage Options

    Compare Auto Insurance Quotes by ZIP Code

    Enter your ZIP code to compare auto insurance quote options. Use equivalent limits, deductibles, drivers, and vehicle information so the prices are comparable.

    Compare the total premium and policy terms, not only the monthly payment.

    Sources

    This article uses current consumer auto-insurance and auto-finance resources. Coverage requirements, lender rules, policy terms, and optional products can change, so confirm time-sensitive details with the insurer, regulator, lender, or issued policy documents.

    1. National Association of Insurance Commissioners — Auto Insurance
    2. National Association of Insurance Commissioners — What Does Auto Insurance Cover?
    3. National Association of Insurance Commissioners — Auto Insurance Shopping Tool
    4. Consumer Financial Protection Bureau — What Is GAP Insurance?
    5. Consumer Financial Protection Bureau — Is GAP Insurance Required?
  • Fred Loya Quote

    Fred Loya Insurance Quote

    Fred Loya currently offers an online quote flow that collects driver, vehicle, coverage, and contact information before presenting a quote. You can start with the official Fred Loya online quote form, call 1-800-444-4040, or use the company’s location finder to reach a local agent.

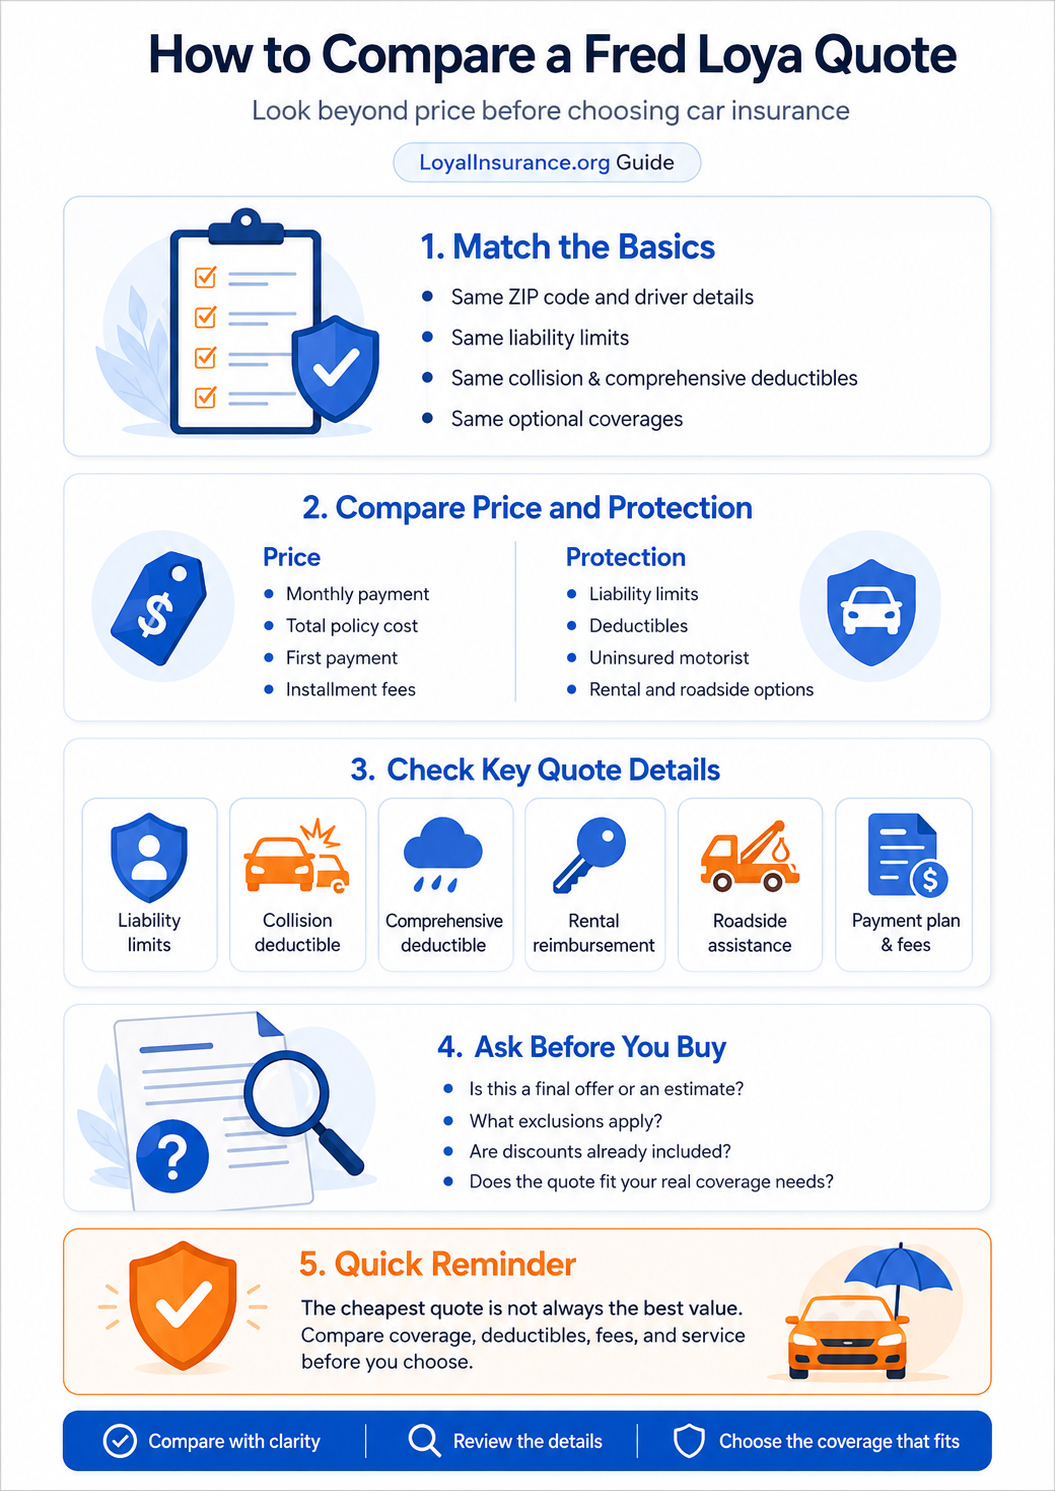
    A useful quote comparison goes beyond the first payment. Match the liability limits, deductibles, collision and comprehensive choices, optional benefits, policy term, total premium, and effective date so you are comparing similar protection rather than different policies with different prices.

    Official quote Online, phone, or local office
    Compare Equivalent coverage
    Check Total premium & deductibles
    Before relying on coverage Confirm issued policy

    What Fred Loya Asks for in an Online Quote

    Fred Loya’s current online quote process asks for identifying and contact information first, then moves through policy-holder, driver, vehicle, coverage, and additional-information stages. The form can request your address, date of birth, marital status, driver’s-license information, driving experience, vehicle details, annual mileage, ownership status, and other information used to build the quote.

    It also asks whether you are currently insured, whether you are a homeowner, and whether you are interested in Auto Pay. Accurate answers matter because the quote is built from the information and coverage choices entered.

    Information worth having ready

    • Driver names, dates of birth, and license information
    • Current address and ZIP code
    • Vehicle VIN or year, make, model, and body style
    • Annual mileage and vehicle ownership status
    • Current insurance information
    • Coverage limits and deductible preferences
    • Any SR-22 requirement that applies to a driver

    Coverage Choices in the Current Fred Loya Quote Flow

    The current quote form presents bodily-injury and property-damage liability selections and asks whether comprehensive and collision should be included. It also shows uninsured and underinsured motorist selections, Medical Payments, Personal Injury Protection, Rental, Towing, and other optional coverage fields.

    If you are trying to keep the quote simple, the tradeoffs behind basic auto insurance coverage are worth checking before choosing the lowest limits or removing physical-damage coverage. A cheaper quote can simply contain less protection.

    Fred Loya quote comparison checklist covering liability limits, deductibles, total premium, optional coverage, and policy details.
    Compare equivalent coverage, deductibles, optional benefits, and total policy cost before choosing a quote.

    Compare the Same Coverage Across Quotes

    The NAIC Auto Insurance Shopping Tool specifically tells consumers to record the coverage limits for each company so that quotes are compared on the same basis. It separates bodily-injury liability, property-damage liability, uninsured/underinsured motorist coverage, medical coverage, collision and comprehensive deductibles, optional benefits, and total premium.

    Quote Detail Why It Matters What to Match
    Liability limits A lower price may reflect lower protection for injuries or property damage. Match bodily-injury and property-damage limits as closely as possible.
    Collision deductible A higher deductible can reduce premium but increases your share after a covered collision. Compare the same deductible amount.
    Comprehensive deductible Different deductibles can make two otherwise similar quotes look very different in price. Match the deductible and confirm comprehensive is actually included.
    UM/UIM and medical coverage These protections can vary significantly by state and quote. Check limits, availability, and whether coverage was selected or rejected.
    Rental and towing Optional benefits can add cost but may reduce specific out-of-pocket expenses later. Compare benefit limits and qualifying situations.
    Total premium The first payment does not show the complete policy cost. Compare the full six-month, annual, or quoted policy-term premium.

    Why Fred Loya Quotes Can Differ From Another Insurer

    Insurers do not necessarily price the same driver in the same way. Triple-I identifies driving record, vehicle use, location, age, vehicle characteristics, selected coverage, deductibles, and other permitted rating information as factors that can affect an auto insurance premium.

    A lower Fred Loya quote may therefore reflect a genuinely different insurer price, different discounts, or different coverage selections. Check the actual inputs and policy structure before deciding what created the difference.

    Price is only one part of the comparison. The Fred Loya Insurance review summarizes current service, claims, office, and consumer-feedback considerations that can help you decide which questions to ask before binding coverage.

    Do Not Compare Only the Monthly Payment

    A quote with a small first payment or monthly installment can still have a higher total cost, different fees, a different policy term, or less coverage. Record the down payment, remaining installments, total premium, and any charges displayed in the quote or policy documents.

    The same applies to deductibles. A policy with a $1,000 deductible can cost less than one with a $500 deductible, but you would need to absorb more of an applicable covered loss before the insurance payment.

    Quote comparison rule: If the limits, deductibles, drivers, vehicles, or optional benefits are different, the prices are not directly comparable.

    Check the Legal Insurer and Policy Documents

    Before relying on the quote, check which legal insurer will issue the policy and make sure that name, the insured vehicles, drivers, limits, deductibles, and effective dates are correct on the issued documents.

    This matters especially when you are comparing a quote against information found elsewhere online. The declarations page and policy forms govern the issued coverage, not a general company description or an old search result.

    Service and Consumer Feedback Belong in the Decision Too

    Price and coverage are central, but service access also matters. Fred Loya currently publishes customer-service, claims, payment, account, and local-office channels. If those service features are important to you, compare them with what another insurer offers before buying.

    Financed or Leased Vehicles Need the Right Physical-Damage Coverage

    A lender or leasing company may require collision and comprehensive coverage even when the state only requires liability. Do not remove physical-damage coverage from the quote simply to reduce the premium without checking the finance or lease agreement.

    Before accepting a quote for a financed vehicle

    • Confirm collision and comprehensive are included when required.
    • Check the deductible against lender requirements.
    • Make sure the lienholder information is correct.
    • Confirm the effective date leaves no gap in required coverage.
    • Compare the added premium with the protection being purchased.

    Quote vs. Active Coverage

    A quote is part of the shopping process; it is not the same thing as proof that coverage is active. Before driving on a replacement policy or canceling an existing one, confirm that the new policy has been issued, check the effective date and time, save the insurance ID card or other proof of coverage, and verify any required payment.

    If the quote will replace an existing insurer, confirm the replacement policy first, save proof of insurance, and only then cancel the old policy for the appropriate date.

    How to Get a Fred Loya Quote

    Fred Loya currently provides three practical starting points: its online quote form, the quotes and customer-service number 1-800-444-4040, and local offices found through the official location finder.

    The online form is the most direct path if you want to enter driver, vehicle, and coverage information yourself. Calling or visiting an office may be more useful when you need help interpreting a coverage option or providing information.

    Official option: Start a Fred Loya quote on FredLoya.com if you specifically want a quote from Fred Loya Insurance.

    Frequently Asked Questions About Fred Loya Quotes

    Can I get a Fred Loya quote online?

    Yes. Fred Loya currently operates an online quote form that collects policy-holder, driver, vehicle, coverage, and additional information before presenting the quote.

    What information does Fred Loya ask for?

    The current form can request contact information, address, date of birth, driver’s-license information, driving experience, vehicle information, annual mileage, current-insurance status, coverage selections, homeowner status, and Auto Pay interest, among other details.

    Does the Fred Loya quote form include collision and comprehensive?

    The current form asks whether you want to include comprehensive and collision and then presents separate collision and comprehensive selections for the vehicle.

    Should I compare the first payment or the total premium?

    Compare the total premium and payment schedule. A low first payment does not necessarily mean the policy has the lowest overall cost.

    Can I cancel my current policy as soon as I receive a cheaper quote?

    Do not cancel an existing policy merely because you received a quote. The sequence for switching car insurance without a coverage gap starts with confirming that the replacement policy is issued and active for the intended date before ending the old coverage.

    Optional: Compare Other Insurers

    Compare Auto Insurance Quotes by ZIP Code

    If you want to compare alternatives in addition to Fred Loya, enter your ZIP code below. Use equivalent limits, deductibles, drivers, and vehicle information when comparing results.

    This comparison is separate from Fred Loya’s official quote form.

    Sources

    This article uses current Fred Loya public quote information and consumer auto-insurance resources. Quote fields, coverage availability, pricing, discounts, and eligibility can change, so confirm time-sensitive details through the current insurer quote process.

    1. Fred Loya Insurance — Official Online Quote Form
    2. Fred Loya Insurance — Quote and Customer Service Contact
    3. Fred Loya Insurance — Official Location Finder
    4. National Association of Insurance Commissioners — Auto Insurance Shopping Tool
    5. National Association of Insurance Commissioners — Auto Insurance
    6. Triple-I — What Determines the Price of an Auto Insurance Policy?
  • Low Income Car Insurance

    Low Income Car Insurance

    Low income car insurance is not one standard insurance product. For most drivers, the goal is to find the lowest sustainable cost while still meeting state requirements and keeping enough protection for the risks they cannot afford to absorb themselves.

    The best starting point is to compare equivalent quotes, check official state resources, and separate the monthly payment from the actual policy. Liability limits, deductibles, optional coverage, installment charges, eligibility rules, and the vehicle itself can all change the total cost.

    Start with State requirements
    Compare Equivalent coverage
    Check Official assistance programs
    Avoid Coverage gaps
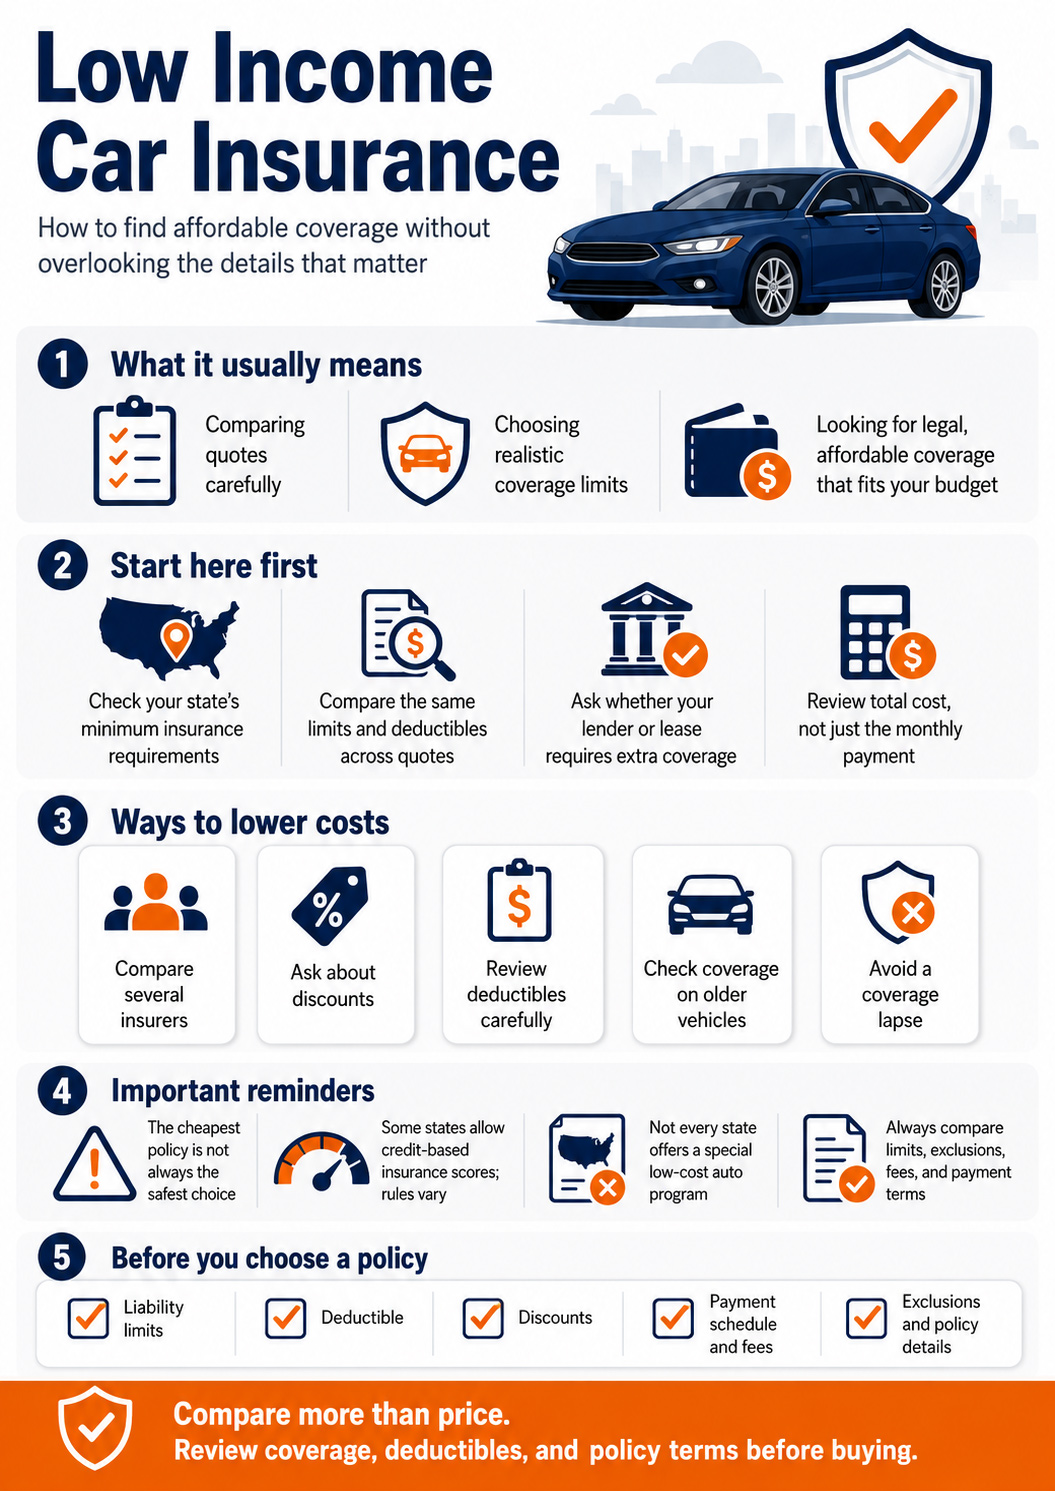
    Low income car insurance overview with state assistance programs, minimum coverage, deductibles, discounts, and quote comparison.

    Low Income Car Insurance vs. Minimum Coverage

    “Low income” describes a household’s financial situation, not a standard insurance coverage level. “Minimum coverage” refers to the insurance or financial-responsibility rules that apply in a particular state. A low-income household may choose minimum coverage for affordability, but the two terms are not interchangeable.

    If you are starting with the lowest legal option, the tradeoffs behind basic auto liability coverage matter because a lower premium can also mean lower liability limits or no physical-damage protection for your own vehicle.

    Minimum does not mean sufficient: A policy can satisfy a legal requirement and still leave substantial costs above the liability limit. Compare the actual dollar limits and exclusions before buying.

    Check for an Official State Low-Cost Program

    Some states offer special mechanisms or assistance programs, but there is no single nationwide “low income car insurance” program. Start with your state insurance department rather than a commercial page that merely uses the phrase “low income.”

    California is a clear example. The California Low Cost Automobile Insurance Program (CLCA) was created for income-eligible drivers who need liability insurance to meet the state’s financial-responsibility requirements. The California Department of Insurance directs consumers to the program and currently lists 1-866-602-8861 for eligibility and certified-agent information.

    California Low Cost Auto Insurance: Key Rules

    California’s current consumer materials say CLCA applicants generally must have household income at or below 250% of the federal poverty level, a valid California driver’s license, be at least 16, own a vehicle worth $25,000 or less, and meet the program’s good-driver requirements or qualify as a new driver. Applicants under 18 must be legally emancipated. Current eligibility should still be checked directly because income thresholds and program rules can be updated.

    The CLCA liability limits are $10,000 for bodily injury or death to one person, $20,000 per accident for bodily injury or death to more than one person, and $3,000 for property damage. California’s standard private-passenger minimum limits increased to 30/60/15 in 2025, but the state says the CLCA limits remain unchanged and still satisfy the program’s financial-responsibility requirements.

    Before applying to any assistance program

    • Confirm the program on an official state insurance-department website.
    • Check current household-income eligibility.
    • Check driver-license and vehicle requirements.
    • Read the liability limits and optional coverage carefully.
    • Confirm the current premium or county-based rate directly with the program.
    • Do not assume a state program is available outside the state that sponsors it.

    Credit-Based Insurance Scores Can Affect Affordability in Some States

    A credit-based insurance score is not the same as a traditional lending credit score. The NAIC says insurers often use credit information in underwriting or rating where state law allows it, while state laws place restrictions on how that information can be used.

    The NAIC also notes that, in most states, a credit-based insurance score cannot be the sole reason to increase rates or deny, cancel, or refuse to renew a policy. Some states impose stronger restrictions or prohibit certain uses, so check the rule that applies where the vehicle is insured.

    If credit information affected the decision: review any adverse-action notice, check the underlying credit report for errors, and compare another insurer because companies can use permitted rating information differently.

    What Actually Changes an Auto Insurance Price?

    Insurance pricing can reflect many permitted factors, including location, driving record, vehicle, coverage selected, deductibles, prior insurance, claims history, mileage or vehicle use, discounts, and other insurer-specific rating information.

    Before buying a car or changing coverage, the car insurance cost factors can help you organize the vehicle, deductible, prior-insurance, and coverage choices that should stay consistent when you request real quotes.

    Cost Factor Why It Can Matter What to Do
    Vehicle Repair cost, value, safety, theft experience, and use can affect pricing. Check insurance costs before purchasing the vehicle.
    Driving record Accidents, tickets, and serious violations can change the insurer’s risk assessment. Use accurate driving information on every quote.
    Coverage limits More liability or physical-damage protection generally changes the premium. Compare equivalent limits across companies.
    Deductible A higher deductible can reduce some physical-damage premiums. Choose only an amount you could realistically pay after a loss.
    Prior insurance Previous coverage is one of the factors identified by the NAIC. Keep prior-coverage dates accurate and avoid unnecessary lapses.
    Discounts Eligibility varies by insurer and state. Ask which discounts are included and which still need verification.

    Ways to Lower Cost Without Cutting the Wrong Protection

    Triple-I recommends shopping around and getting at least three price quotes. It also recommends checking insurance costs before buying a vehicle, considering higher deductibles that you could afford, evaluating collision or comprehensive on older vehicles, and asking about discounts.

    Changes worth comparing

    • Equivalent quotes from several insurers
    • Different physical-damage deductibles
    • Available multi-policy or multi-vehicle discounts
    • Low-mileage or other verified discounts where offered
    • Collision or comprehensive on an older paid-off vehicle

    Changes that need more caution

    • Reducing liability limits
    • Removing coverage required by a lender or lease
    • Choosing a deductible you could not pay after a claim
    • Canceling before replacement coverage is active
    • Ignoring fees or the total policy premium

    Higher Deductibles Can Lower Premiums but Increase Claim-Time Risk

    A higher collision or comprehensive deductible can reduce the premium, but the savings only help if the deductible is still affordable when a claim happens. For a household with little emergency savings, moving from a manageable deductible to a much larger one can simply shift the financial problem from the monthly bill to the day of the loss.

    Compare the annual premium difference against the extra amount you would need to pay after a covered claim. If the vehicle is financed or leased, also check the loan or lease agreement before changing physical-damage coverage.

    Older Paid-Off Vehicles Need a Different Calculation

    Collision and comprehensive can become less cost-effective as a vehicle loses value, particularly when the car is paid off. Triple-I recommends evaluating whether those coverages still make sense on an older vehicle rather than automatically renewing the same structure every year.

    Dropping physical-damage coverage means accepting the risk of paying for your own vehicle repair or replacement after certain losses. Compare the vehicle’s value, annual coverage cost, deductible, and your ability to replace the car before making that decision.

    Avoid a Coverage Lapse While Looking for a Cheaper Policy

    Cutting cost should not create a period with no insurance. If you find a cheaper replacement, confirm that the new policy has been issued, verify its effective date and time, and save proof of insurance before the old policy’s cancellation takes effect.

    When replacing an existing policy, confirm that the new coverage has been issued, verify its effective date and time, save proof of insurance, and only then cancel the old policy for the appropriate date.

    If a payment is becoming difficult: contact the current insurer before assuming there is a grace period or simply allowing the policy to cancel. Ask about the amount due, cancellation date, available payment methods, and whether a lower-cost policy structure is available before coverage ends.

    What If Every Quote Still Feels Too Expensive?

    First make sure you are comparing equivalent policies. A quote can look cheaper or more expensive because the liability limits, deductibles, drivers, vehicles, optional benefits, policy term, or payment plan are different.

    Steps worth trying

    • Get quotes from several insurers rather than relying on one company.
    • Ask for both the legal minimum and a higher-limit option so you can see the price difference.
    • Check whether the vehicle itself is a major cost driver.
    • Ask which discounts have actually been applied.
    • Check the state insurance department for official assistance, assigned-risk, or residual-market resources where available.
    • Review whether a different deductible is affordable rather than simply choosing the highest one.
    • Compare the total premium and fees, not just the monthly installment.

    Where Fred Loya Fits Into an Affordability Comparison

    Fred Loya can be one company to compare in states where it operates, particularly for drivers who value local-office access or want an auto-focused insurer. It should still be compared on the same basis as every other company: equivalent liability limits, deductibles, optional coverage, total premium, fees, and policy terms.

    Do not assume that “no credit check,” a local office, or a lower first payment automatically makes a policy the least expensive overall. The issued policy and total premium matter more than the marketing label.

    If another insurer offers a policy that fits your budget better, the timing for switching car insurance without a coverage gap matters just as much as the price difference. Confirm the replacement coverage before ending the current policy.

    Frequently Asked Questions About Low Income Car Insurance

    Is there a nationwide low-income auto insurance program?

    No single nationwide program exists. Assistance options depend on the state. Check the official state insurance department or assigned-risk plan for current programs and eligibility.

    Does California have a low-cost auto insurance program?

    Yes. California operates the California Low Cost Automobile Insurance Program for qualifying drivers. Current eligibility and rates should be checked directly with the program or California Department of Insurance.

    Does the California program use the normal 30/60/15 liability limits?

    No. California says CLCA uses lower 10/20/3 liability limits that remain legally valid within that special program, even though the state’s standard private-passenger minimum limits increased in 2025.

    Will a higher deductible always save enough money to be worthwhile?

    No. A higher deductible can lower some premiums, but the savings should be compared with the extra amount you would have to pay after a covered loss.

    Can credit affect car insurance?

    In states where the practice is allowed, insurers may use credit-based insurance scores as one rating or underwriting factor. State restrictions vary, and these scores are different from traditional lending credit scores.

    Compare Affordable Options

    Compare Auto Insurance Quotes by ZIP Code

    Enter your ZIP code to compare auto insurance quote options. Match equivalent coverage limits and deductibles, then compare the total premium and policy terms.

    Compare the actual policy, not only the monthly payment.